The Accounts · daily brief
18 August 2026
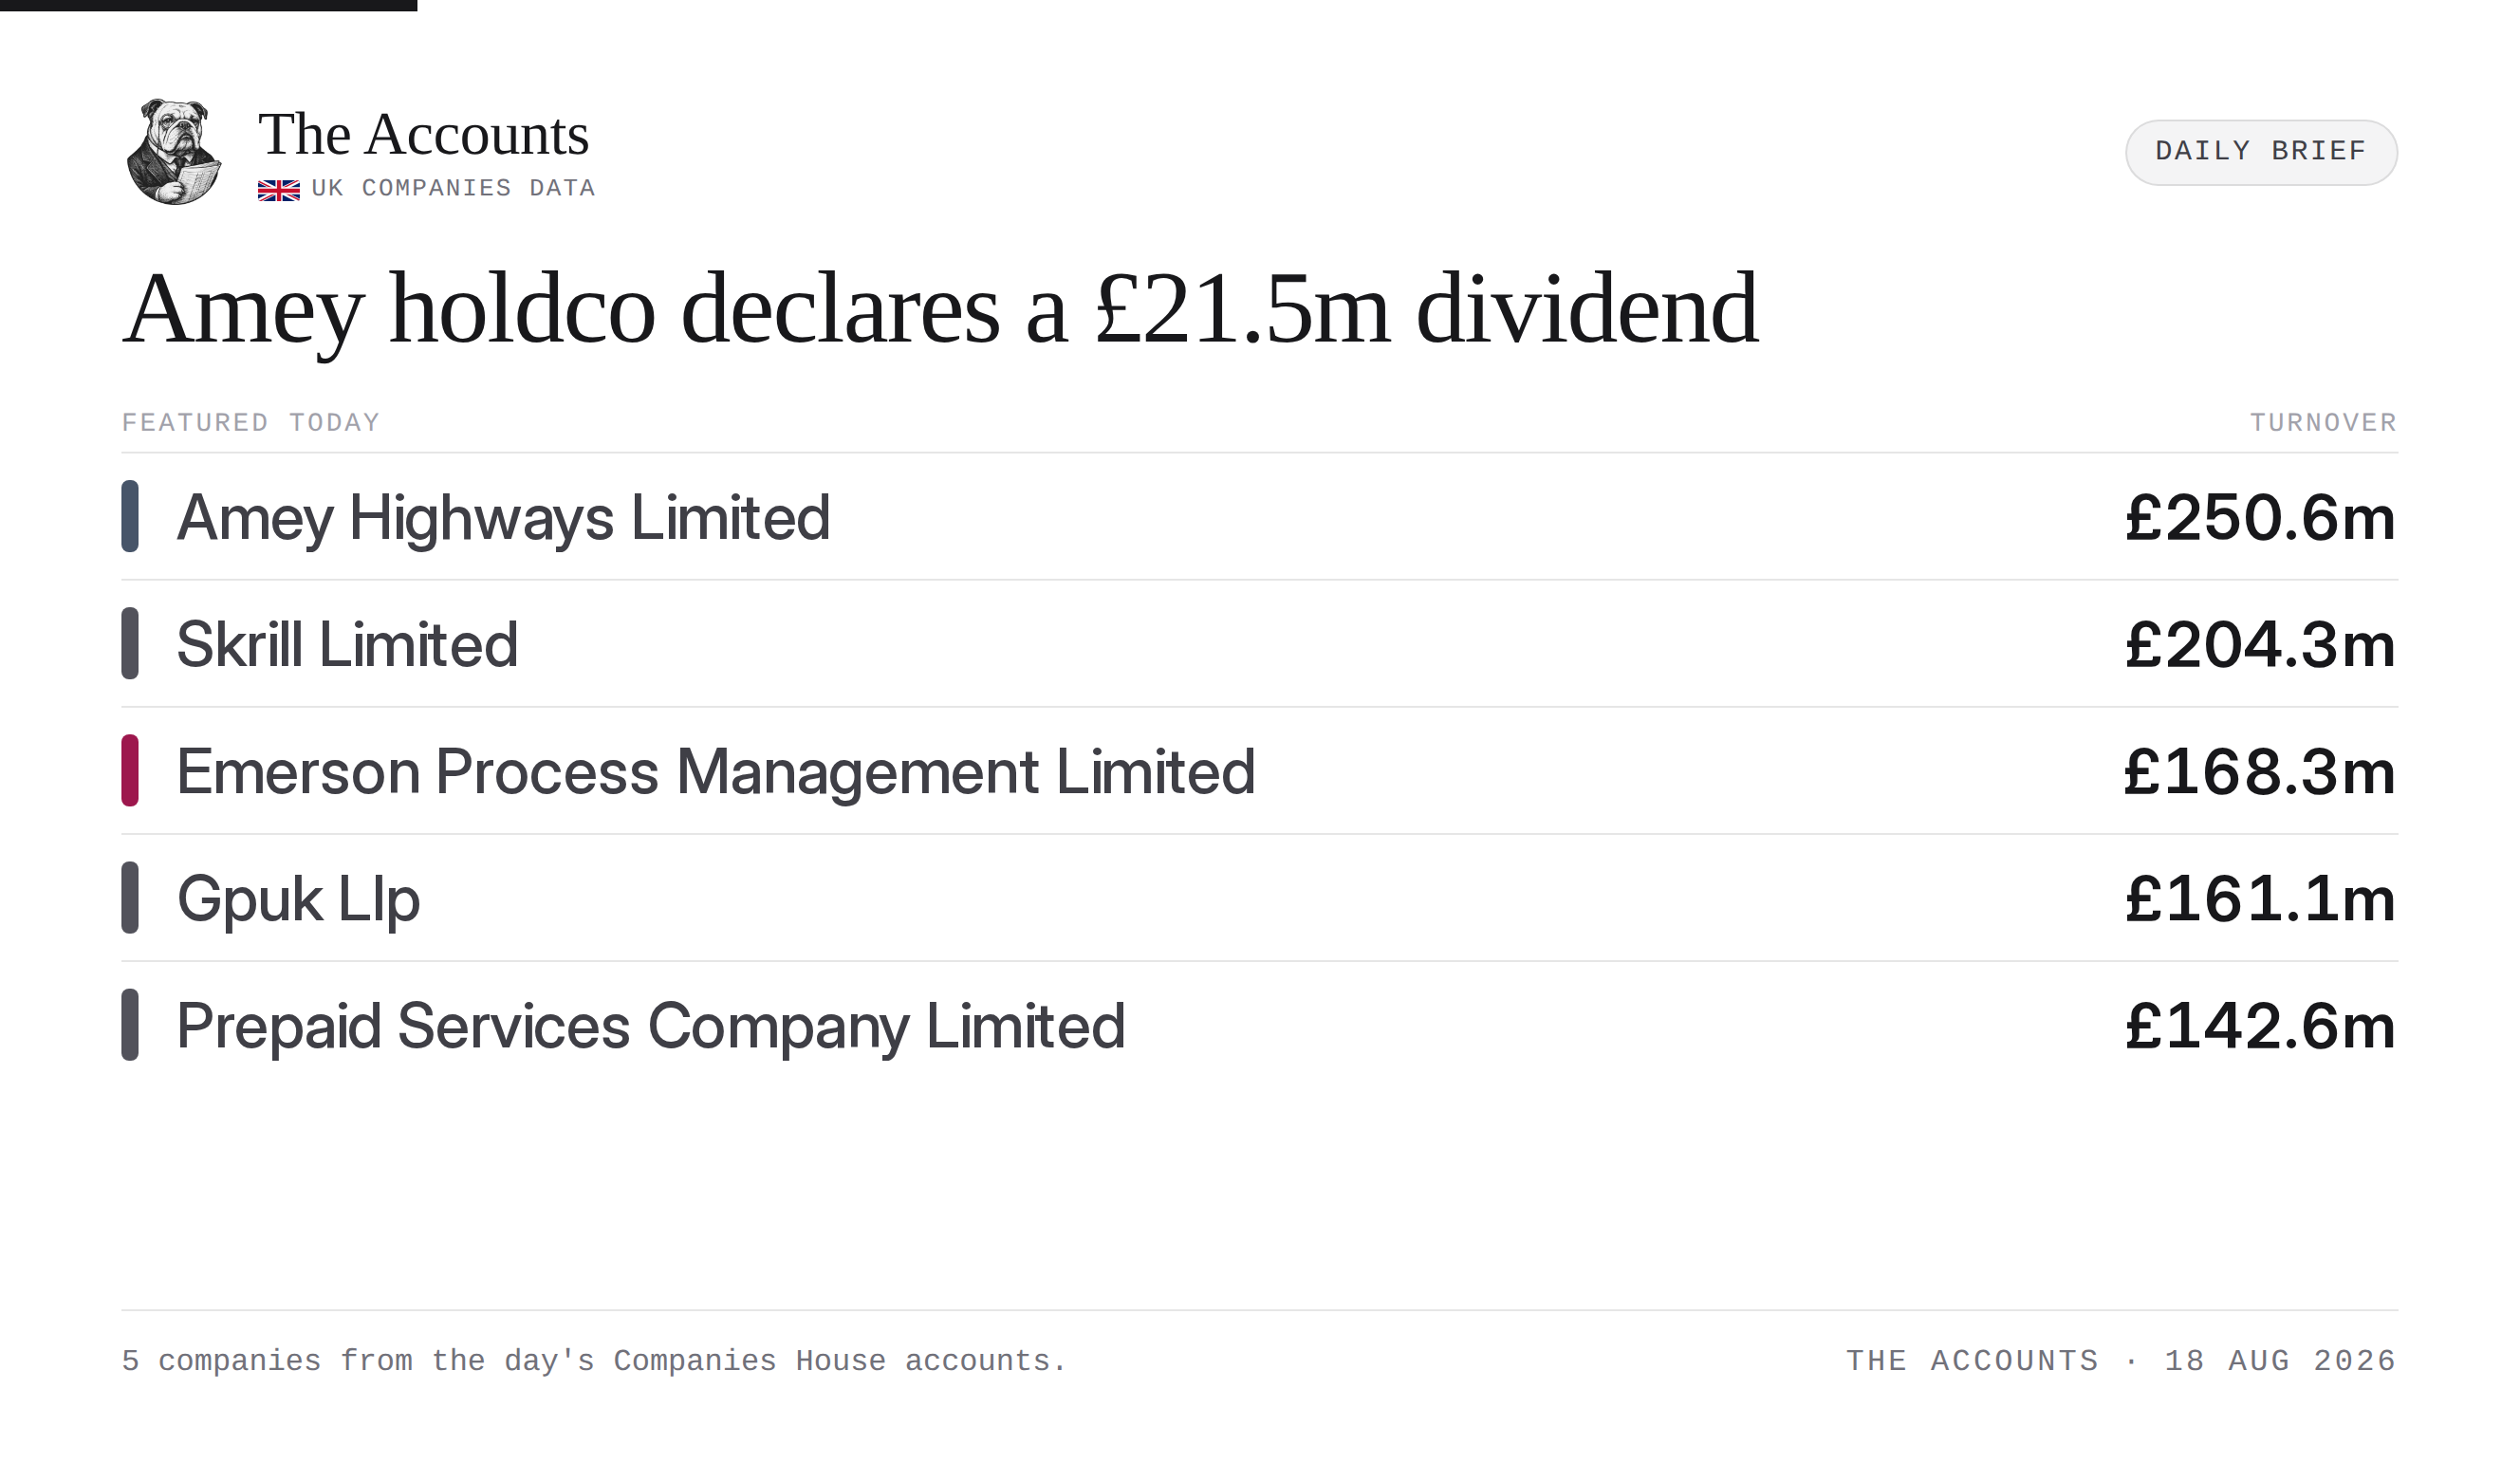
Amey holdco declares a £21.5m dividend
The takeaways
- Amey Investments paid out a £21.5m dividend while holding £1.09m in net assets
- Skrill's operating profit fell 18% to £61.8m as administrative expenses expanded by over £9m
- Revenue at Global Payments' UK arm slid 10% to £161.1m alongside higher scheme fee processing costs
Hiring signals · who grew, who shrank
Hiring
- Trilitech Limited 81 → 144 staff ▲ +78% staff cost +41%
- Mtl Advanced Ltd 303 → 419 staff ▲ +38% staff cost +38%
Cutting
- Wessex Retail Limited 408 → 248 staff ▼ −39% staff cost −1%
- Park Communications Limited 206 → 167 staff ▼ −19% staff cost +20%
Average headcount from the accounts filed yesterday — a look back at last year's payroll, not a live hiring tracker.
Filing of note
Amey Investments Limited
The entity operates as an investment holding subsidiary within the Amey group, a major provider of infrastructure consultancy and support services ultimately owned by Project Ardent Topco Ltd.
Paid a £21.5m dividend on £1.1m of equity.
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £109k | £184k | ▼ −41% |
| Gross profit | £65,000 | £176k | ▼ −63% |
| Admin expenses | £1,000 | £1,000 | ▲ −0% |
| Operating profit | £64,000 | £176k | ▼ −64% |
| Finance costs | £29,000 | £0 | |
| Profit before tax | £282k | £842k | ▼ −67% |
| Net profit | £235k | £662k | ▼ −65% |
| Cash & balance sheet | |||
| Cash | £483k | £196k | ▲ +146% |
| Net assets | £1.1m | £856k | ▲ +27% |
| Dividends paid | £21.5m | — | |
A notable filing comes from this Amey investment holding subsidiary, which paid out a £21.5m dividend alongside £1.09m of net assets. Turnover for the year was £109k, yielding an operating profit of £64k. A classic holdco structure, transferring capital up the group chain.
Amey Highways Limited [1]
The company is the road network design and maintenance division of the British infrastructure engineering group Amey, which is jointly owned by private equity firms Buckthorn Partners and One Equity Partners.
Contract growth
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £250.6m | £192.9m | ▲ +30% |
| Gross profit | £19.5m | £13.9m | ▲ +40% |
| Admin expenses | £14.9m | £10.2m | ▲ +47% |
| Operating profit | £4.6m | £3.8m | ▲ +22% |
| Finance costs | £413k | £569k | ▼ −27% |
| Profit before tax | £5.7m | £3.7m | ▲ +55% |
| Net profit | £4.3m | £2.8m | ▲ +55% |
| Cash & balance sheet | |||
| Cash | £8m | £8.7m | ▼ −8% |
| Net assets | £20.7m | £16.4m | ▲ +26% |
| People & pay | |||
| Director pay | £1.3m | £1.3m | ▲ +4% |
| Highest-paid director | £1.1m | £1m | ▲ +7% |
A steady year of trading for the infrastructure group's road maintenance division. Turnover rose 30% to £250.5m, which the filing attributes to increased activity on its Kent contract. That extra volume coincided with operating profit rising to £4.6m.
Skrill Limited [2]
Operating formerly as Moneybookers, the company provides a digital multi-currency wallet and online payment platform as a subsidiary of the global payments group Paysafe Limited.
Margin contraction
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £204.3m | £196.9m | ▲ +4% |
| Gross profit | £151.7m | £155.7m | ▼ −3% |
| Admin expenses | £90.2m | £80.9m | ▲ +12% |
| Operating profit | £61.8m | £75.4m | ▼ −18% |
| Finance costs | £784k | £871k | ▼ −10% |
| Profit before tax | £63.2m | £77.1m | ▼ −18% |
| Net profit | £59m | £68.8m | ▼ −14% |
| Cash & balance sheet | |||
| Cash | £65.9m | £36.8m | ▲ +79% |
| Net assets | £120.5m | £143.6m | ▼ −16% |
| Dividends paid | £82.3m | £89.9m | ▼ −8% |
| People & pay | |||
| Avg. headcount | 66 | 73 | ▼ −10% |
| Staff cost | £9.7m | £10.4m | ▼ −7% |
| Director pay | £652k | £790k | ▼ −17% |
| Highest-paid director | £342k | £856k | ▼ −60% |
A margin contraction on the bottom line for the digital wallet provider. While turnover rose slightly to £204.3m, operating profit fell 18% to £61.8m. That drop came as administrative expenses expanded by £9.3m to £90.2m, while average headcount dropped from 73 to 66.
Emerson Process Management Limited [3]
Operating within the Emerson Automation Solutions division, the company serves as a UK manufacturing and services subsidiary of the US-listed engineering group Emerson Electric Co., specialising in industrial process management systems.
Reduced headcount
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £168.3m | £160.9m | ▲ +5% |
| Gross profit | £61.9m | £62.3m | ▼ −1% |
| Admin expenses | £29.5m | £32.1m | ▼ −8% |
| Cash & balance sheet | |||
| Net assets | £97.5m | £84.6m | ▲ +15% |
| Dividends paid | £55.2m | £61m | ▼ −9% |
| People & pay | |||
| Avg. headcount | 495 | 522 | ▼ −5% |
| Staff cost | £42.2m | £42.2m | ▼ −0% |
| Director pay | £1.1m | £1m | ▲ +6% |
| Highest-paid director | £373k | £298k | ▲ +25% |
The UK manufacturing arm of the US engineering group operated with a reduced headcount. Turnover rose slightly to £168.2m, and underlying trading profit improved to £32.4m as average headcount fell by 27 alongside lower administrative expenses. The filing notes the cessation of less profitable product lines contributed to the improved margins.
Gpuk Llp [4]
Trading as Global Payments, the partnership acts as the UK merchant acquiring arm of the wider Global Payments group, providing electronic point-of-sale payment processing and terminal rental services.
Lower revenue
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £161.1m | £179.5m | ▼ −10% |
| Admin expenses | £84.3m | £88.5m | ▼ −5% |
| Finance costs | £4.1m | £5.3m | ▼ −22% |
| Profit before tax | £68.1m | £83.7m | ▼ −19% |
| Net profit | £68.1m | £83.7m | ▼ −19% |
The UK merchant acquiring arm of Global Payments saw a contraction at the top line. Turnover fell 10% to £161.1m, a drop the partnership attributes to an increase in fee processing costs charged by schemes. Profit before tax followed suit, dropping to £68.1m alongside a £4.2m reduction in administrative expenses.
Prepaid Services Company Limited [5]
Operating as the prepaid card issuing entity for the Paysafecard group, the company is an FCA-regulated electronic money institution providing payment solutions and branded cards to merchants and consumers.
Capital light
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £142.6m | £128.6m | ▲ +11% |
| Gross profit | £78m | £69.4m | ▲ +12% |
| Admin expenses | £35m | £33.9m | ▲ +3% |
| Operating profit | £43.1m | £35.5m | ▲ +21% |
| Finance costs | £11,305 | £2,027 | ▲ +458% |
| Profit before tax | £43.9m | £37.4m | ▲ +17% |
| Net profit | £43.8m | £37.5m | ▲ +17% |
| Cash & balance sheet | |||
| Cash | £12.1m | £5.5m | ▲ +121% |
| Net assets | £232.5m | £214.4m | ▲ +8% |
| Dividends paid | £25.7m | £64.2m | ▼ −60% |
| People & pay | |||
| Avg. headcount | 5 | 4 | ▲ +25% |
| Staff cost | £608k | £294k | ▲ +107% |
A steady set of consolidated accounts for Paysafecard's e-money institution. Turnover climbed 11% to £142.6m, with operating profit rising to £43.1m. The company recorded these figures on a narrow footprint, operating with an average of just five employees.
If I could pay out twenty times my net worth, I'd buy a bigger bed.
Sources
- Amey Highways Limited
- Skrill Limited
- Emerson Process Management Limited
- Gpuk Llp
- Prepaid Services Company Limited