The Accounts · daily brief
31 August 2026
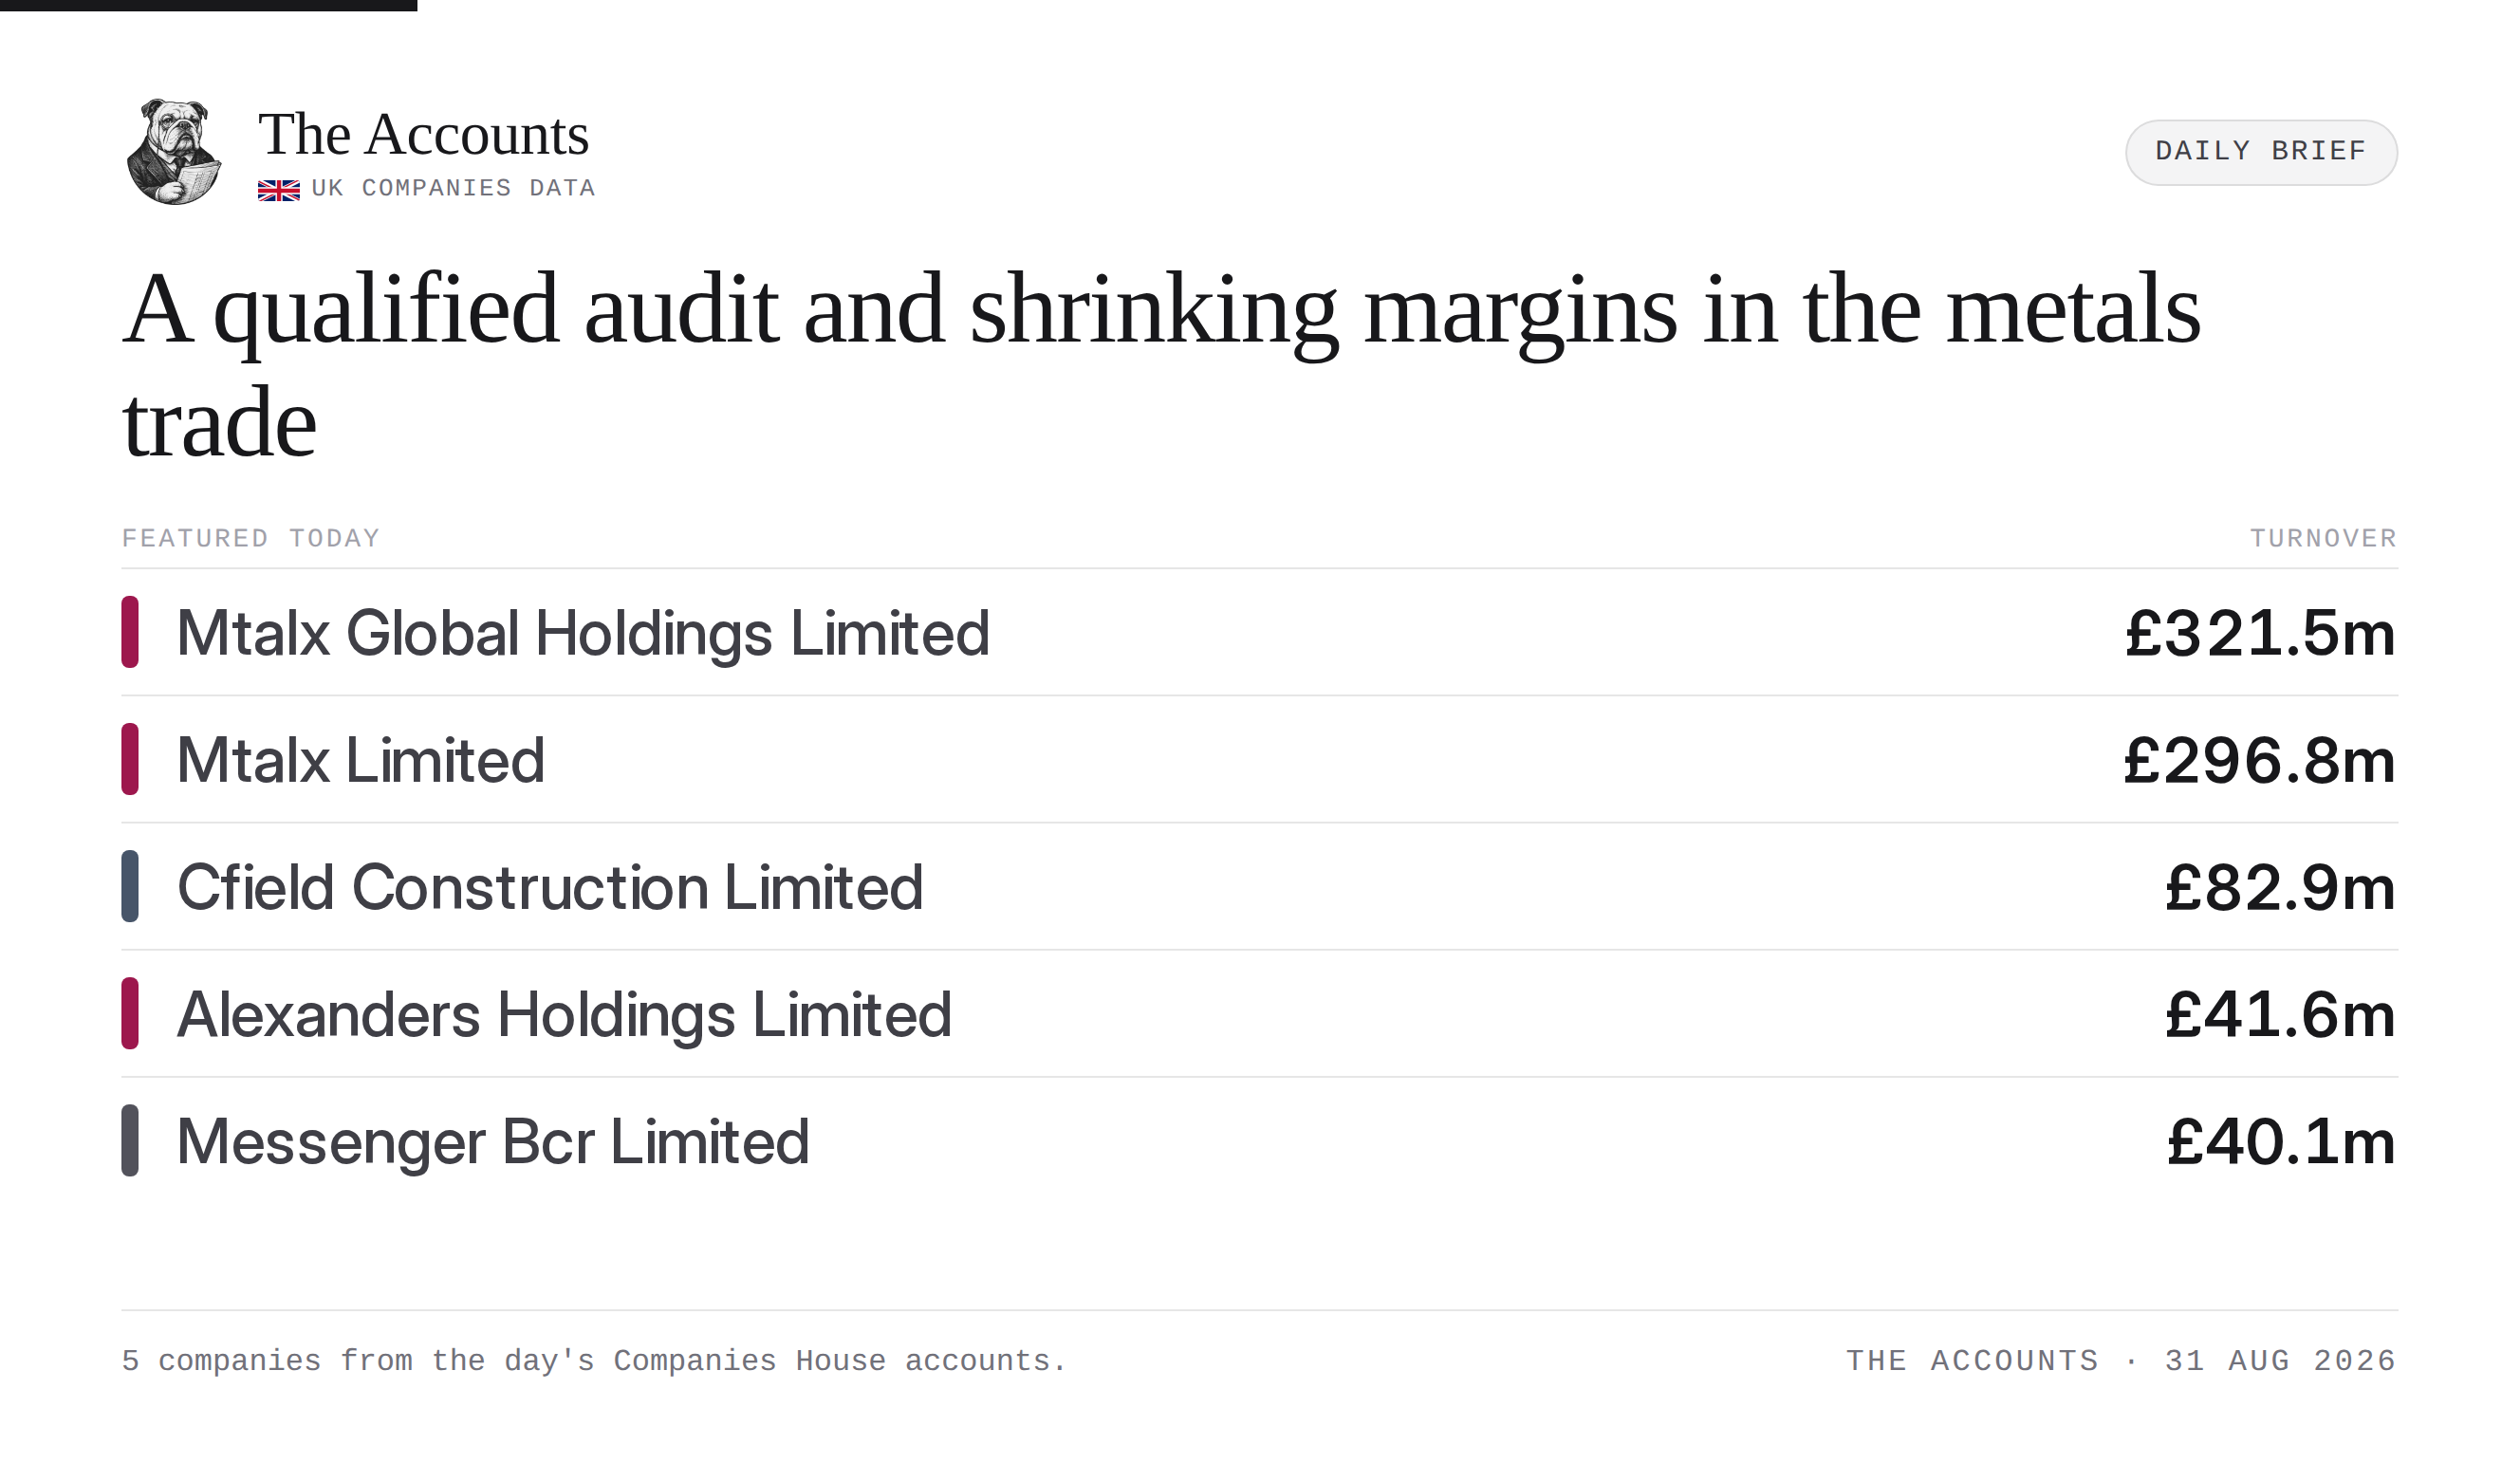
A qualified audit and shrinking margins in the metals trade
The takeaways
- J. & J.G. Dickson's accounts arrive with a qualified audit opinion, a detail worth noting
- CField Construction shed significant revenue but swung back to a £3.1m operating profit
- Global metals trader MTALX saw its group turnover drop 24% as commodity pricing softened
Hiring signals · who grew, who shrank
Hiring
- Messenger Bcr Limited 113 → 134 staff ▲ +19% staff cost +14%
- Premium Payroll Solutions Limited 136 → 158 staff ▲ +16% staff cost +14%
Cutting
- Vision Modular Systems Uk Limited 141 → 119 staff ▼ −16% staff cost −19%
- Aluk (Gb) Limited 147 → 132 staff ▼ −10% staff cost −2%
Average headcount from the accounts filed yesterday — a look back at last year's payroll, not a live hiring tracker.
Filing of note
J. & J.G. Dickson & Son Limited
The company operates as an independent, family-run dispensing chemist based in Rutherglen, Glasgow.
Auditor issued a qualified opinion.
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £14.7m | £13.6m | ▲ +9% |
| Gross profit | £6.7m | £5.8m | ▲ +16% |
| Admin expenses | £6.8m | £5.6m | ▲ +21% |
A notable filing comes from this Glasgow pharmacy, which lands on the desk with a qualified audit opinion. The top line shows steady growth, with turnover edging up 8% to £14.7m and the gross profit margin widening to 46%. The qualified sign-off from the auditor is a detail worth noting in the full accounts.
Mtalx Global Holdings Limited [1]
MTALX Global Holdings Limited is the parent entity of MTALX, an international trading group specialising in the supply and logistics of non-ferrous metals, alloys, and plastic resins for the metallurgical industry.
Margin squeeze
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £321.5m | £423.5m | ▼ −24% |
| Gross profit | £17.5m | £26.3m | ▼ −34% |
| Admin expenses | £9.2m | £8.8m | ▲ +4% |
| Operating profit | £6.4m | £14.9m | ▼ −57% |
| Finance costs | £5.1m | £6.2m | ▼ −17% |
| Profit before tax | £1.3m | £8.7m | ▼ −85% |
| Net profit | £365k | £6m | ▼ −94% |
| Cash & balance sheet | |||
| Cash | £4.3m | £2.4m | ▲ +80% |
The parent company of this international metals trader saw a contraction at the top line, with turnover falling 24% to £321.5m. The filing attributes this to weaker global demand and softer commodity pricing during the period. This contraction in trade saw operating profit fall 57% to £6.4m, though the group remains profitable overall.
Mtalx Limited [2]
Operating globally from a London headquarters, the company is an international trader specialising in the wholesale of ferrous and non-ferrous metals, alloys, and plastic resins, acting as a wholly owned subsidiary of Mtalx Global Holdings Ltd.
Profit halved
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £296.8m | £367.5m | ▼ −19% |
| Gross profit | £17.8m | £25.8m | ▼ −31% |
| Admin expenses | £7.3m | £6m | ▲ +21% |
| Operating profit | £8.8m | £17.3m | ▼ −49% |
| Finance costs | £5.1m | £6.2m | ▼ −17% |
| Profit before tax | £3.7m | £11.1m | ▼ −67% |
| Net profit | £2.7m | £8.3m | ▼ −67% |
| Cash & balance sheet | |||
| Cash | £2.1m | £124k | ▲ +1615% |
| Net assets | £41.2m | £39.5m | ▲ +4% |
| Dividends paid | £1m | £150k | ▲ +567% |
| People & pay | |||
| Avg. headcount | 33 | 33 | ▲ −0% |
| Staff cost | £2.4m | £2.5m | ▼ −1% |
| Director pay | £487k | £410k | ▲ +19% |
| Highest-paid director | £185k | £180k | ▲ +3% |
The main operating subsidiary mirrors the parent's contraction, shedding 19% of its revenue to land at £296.8m. Operating profit halved to £8.8m as geopolitical and tariff headwinds impacted the period. Alongside this contraction in trade, total directors' remuneration rose 19% to £487k.
Cfield Construction Limited [3]
Operating as a subsidiary of Cfield CS Group Limited, the business is a building and civil engineering contractor that undertakes commercial and residential construction projects across the UK and Ireland.
Profitable contraction
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £82.9m | £119.2m | ▼ −30% |
| Gross profit | £7.7m | £2.2m | ▲ +252% |
| Admin expenses | £4.6m | £3.4m | ▲ +35% |
| Operating profit | £3.1m | −£1.2m | ▲ +356% |
| Profit before tax | £3.3m | −£1.2m | ▲ +368% |
| Net profit | £3m | −£1.2m | ▲ +352% |
| Cash & balance sheet | |||
| Cash | £13.5m | £6.5m | ▲ +109% |
| Net assets | £8.2m | £5.2m | ▲ +58% |
| People & pay | |||
| Avg. headcount | 52 | 61 | ▼ −15% |
| Staff cost | £5.3m | £6m | ▼ −11% |
| Director pay | £20,000 | £98,635 | ▼ −80% |
| Highest-paid director | £20,000 | £98,635 | ▼ −80% |
A clear case of margin improvement on lower volume. Turnover dropped from £119.2m to £82.9m, but operating profit swung from a £1.2m loss to a £3.1m gain. The filing attributes the shift to the completion of challenging legacy projects in the prior year, which allowed the underlying margin to improve.
Alexanders Holdings Limited [4]
Trading as Alexanders Motor Group, the company is a privately owned automotive dealership network based in North East England, specialising in the sale of new and used cars and light commercial vehicles.
Strong growth
| Line | FY26 | FY25 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £41.6m | £35.9m | ▲ +16% |
| Gross profit | £2.2m | £1.6m | ▲ +42% |
| Admin expenses | £1.1m | £1.1m | ▲ +1% |
| Operating profit | £1.3m | £689k | ▲ +85% |
| Finance costs | £21,496 | £13,450 | ▲ +60% |
| Profit before tax | £1.4m | £805k | ▲ +71% |
| Net profit | £1m | £601k | ▲ +71% |
| Cash & balance sheet | |||
| Dividends paid | £116k | £276k | ▼ −58% |
| People & pay | |||
| Avg. headcount | 45 | 45 | ▲ −0% |
| Staff cost | £1.9m | £1.8m | ▲ +1% |
| Director pay | £11,725 | £11,950 | ▼ −2% |
This North East dealership group recorded a steady 16% increase in turnover to £41.6m. The higher volume coincided with a margin expansion, nearly doubling operating profit to £1.27m. The filing notes a significant rise in business rates as government relief tapers off, but the core operation remains profitable for the period.
Messenger Bcr Limited [5]
Operating as the Messenger BCR Group, this privately held parent company oversees subsidiaries including Messenger Construction Ltd and Messenger Building Repairs Ltd, specialising in the conservation, restoration, and main contracting of historic buildings, monuments, and bespoke homes.
Margin pressure
| Line | FY26 | FY25 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £40.1m | £35.2m | ▲ +14% |
| Gross profit | £8.1m | £7.9m | ▲ +3% |
| Admin expenses | £6.9m | £6.5m | ▲ +6% |
| Operating profit | £1.3m | £1.4m | ▼ −7% |
| Finance costs | £108k | £115k | ▼ −6% |
| Profit before tax | £1.2m | £1.3m | ▼ −8% |
| Net profit | £803k | £990k | ▼ −19% |
| Cash & balance sheet | |||
| Cash | £663k | £1.3m | ▼ −50% |
| Net assets | £6.2m | £5.4m | ▲ +15% |
| Dividends paid | £18,000 | £18,000 | ▲ −0% |
| People & pay | |||
| Avg. headcount | 134 | 113 | ▲ +19% |
| Staff cost | £7.2m | £6.3m | ▲ +14% |
| Director pay | £209k | £178k | ▲ +17% |
| Highest-paid director | £104k | — | |
Revenue at this heritage construction specialist rose 14% to £40.1m, but the top-line growth did not translate to the bottom line. Operating profit slipped 7% to £1.28m as administrative expenses expanded. Staff costs increased during the period, with average headcount rising from 113 to 134 alongside the higher revenue figure.
A good day for legacy contracts rolling off, less so for the global metals trade.
Sources
- Mtalx Global Holdings Limited
- Mtalx Limited
- Cfield Construction Limited
- Alexanders Holdings Limited
- Messenger Bcr Limited