The Accounts · daily brief
14 September 2026
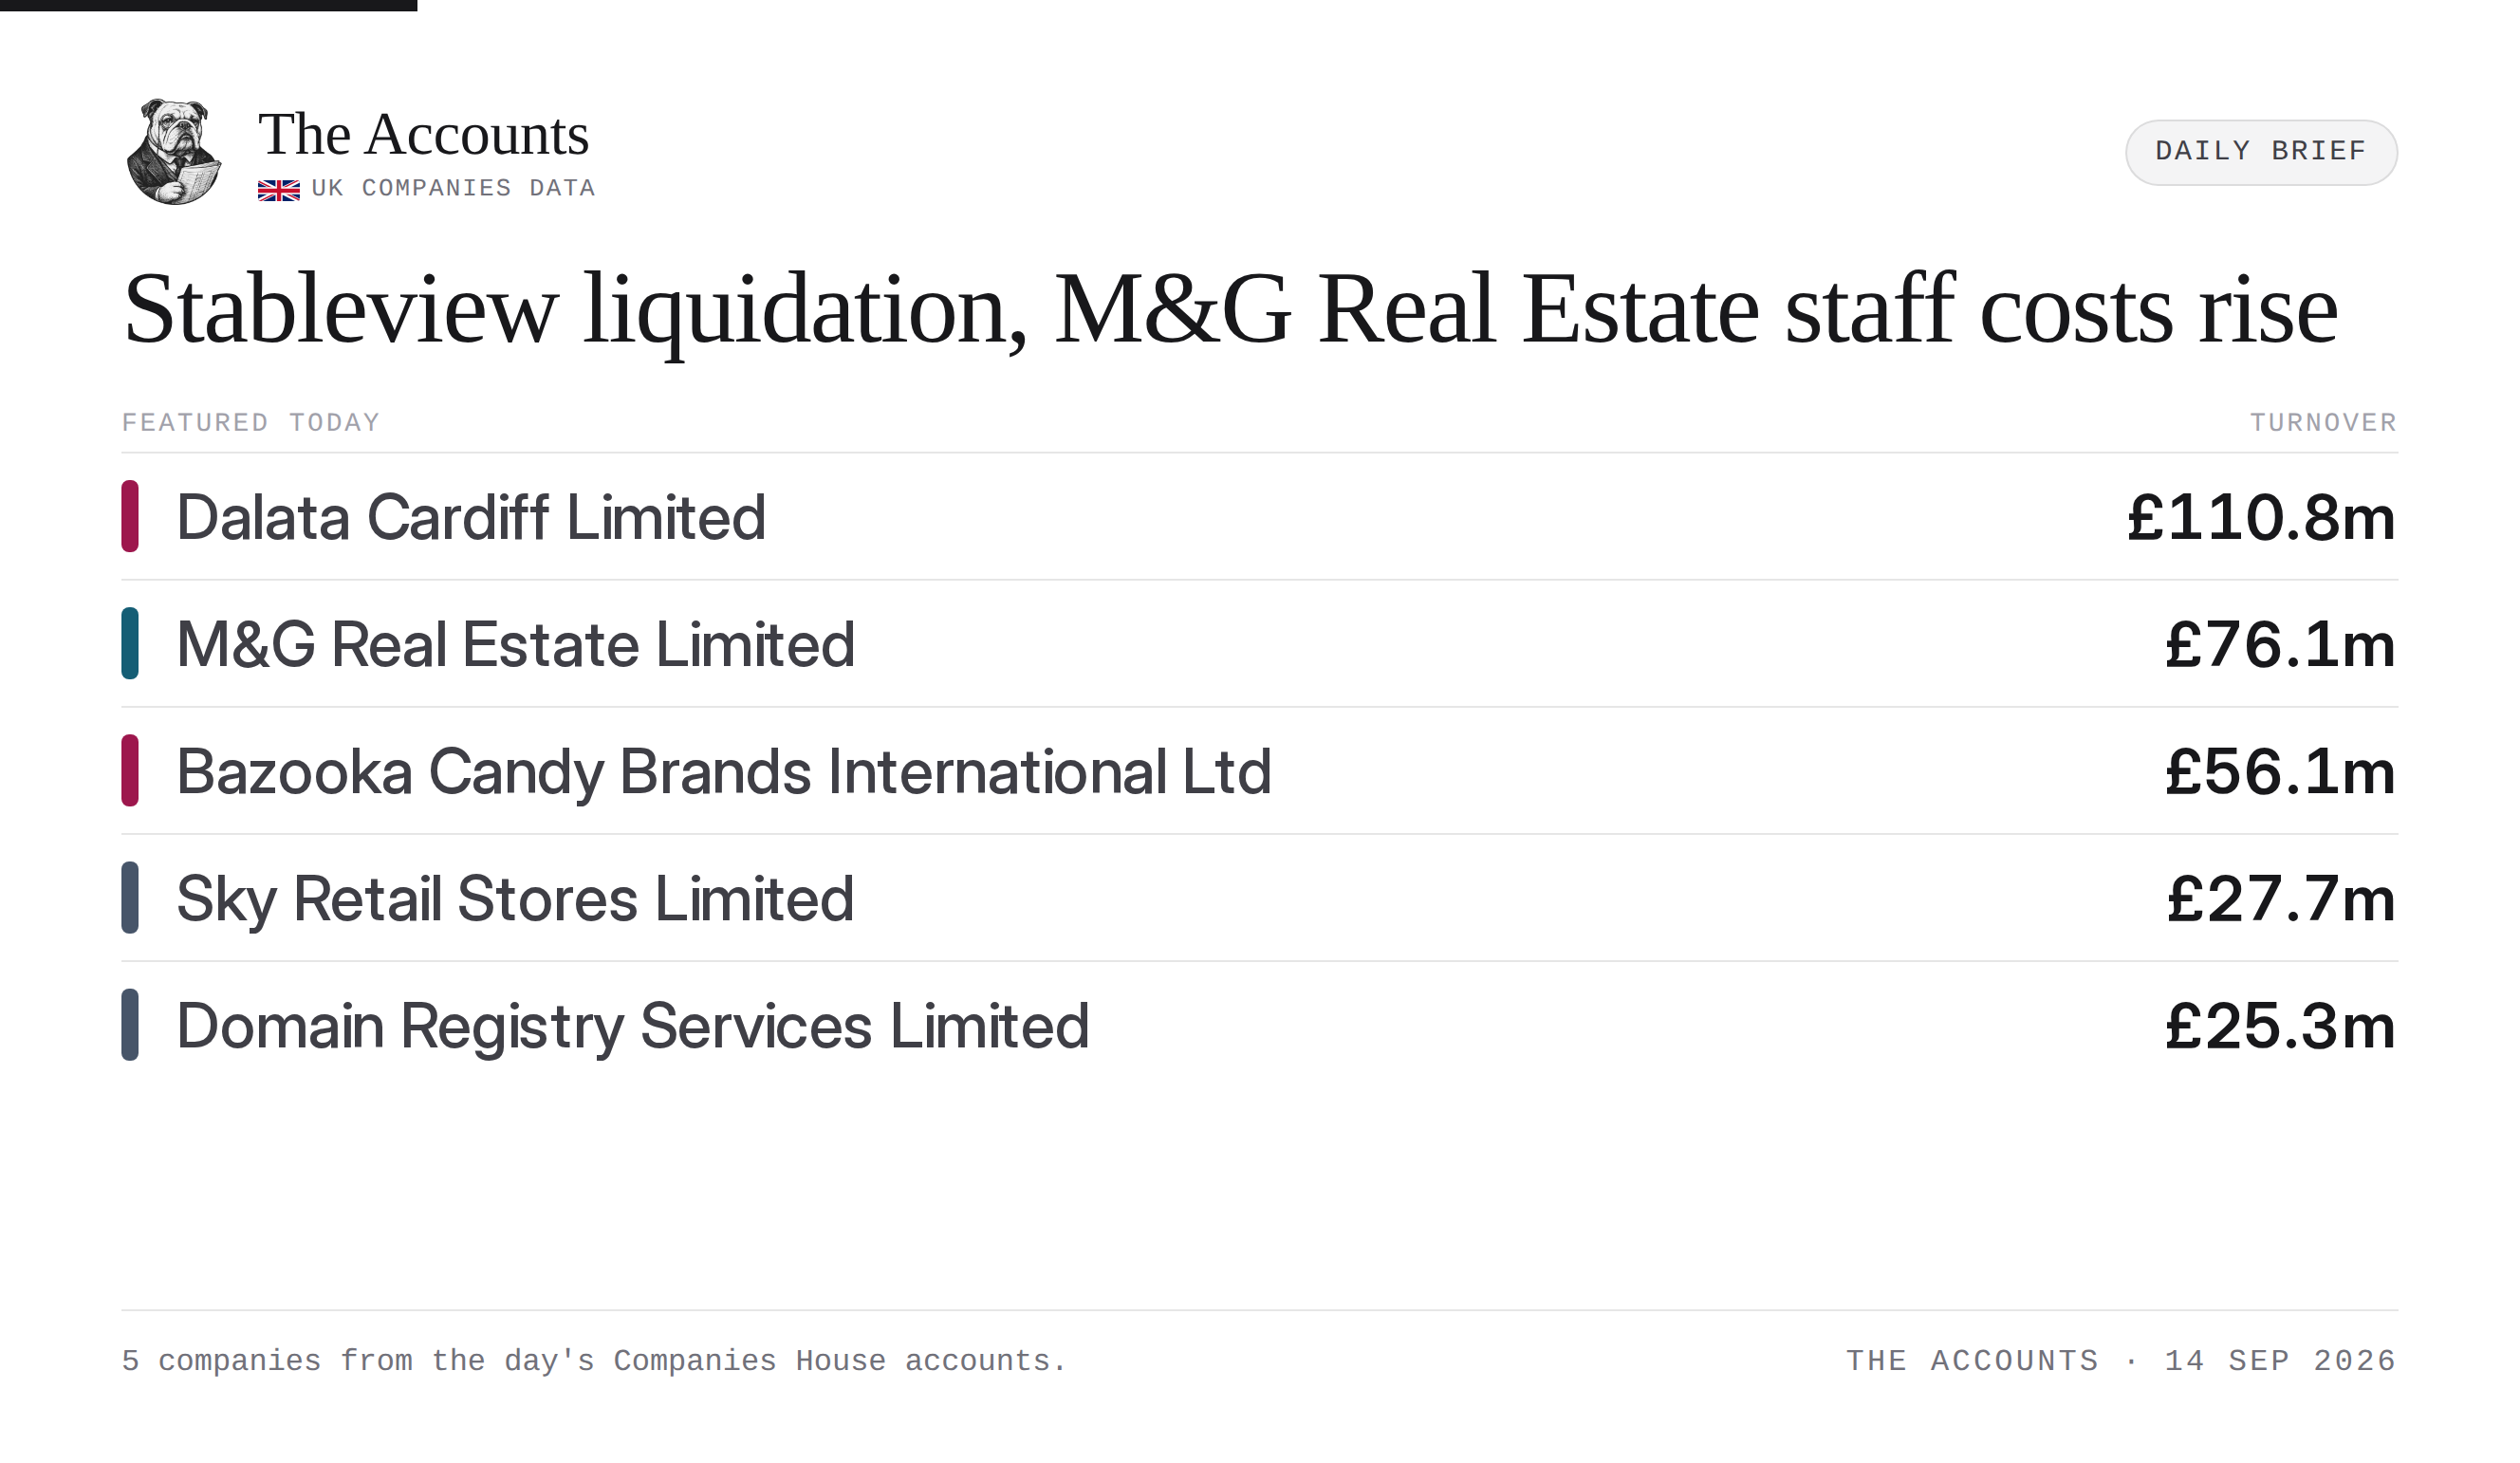
Stableview liquidation, M&G Real Estate staff costs rise
The takeaways
- Stableview accounts are prepared on a break-up basis ahead of an intended liquidation
- Average headcount at M&G Real Estate fell by 17% while total staff costs rose 9% to £32.8m
- Dalata Cardiff turnover grew 12% to £110.8m but pre-tax losses widened alongside heavy lease charges
Hiring signals · who grew, who shrank
Hiring
None worth flagging.
Cutting
- Dhg Castle Limited 38 → 31 staff ▼ −18% staff cost +3%
- M&G Real Estate Limited 173 → 143 staff ▼ −17% staff cost +9%
Average headcount from the accounts filed yesterday — a look back at last year's payroll, not a live hiring tracker.
Filing of note
Stableview Limited
Operating from the group's London headquarters, the company acts as a financial intermediation subsidiary within the M&G investment management group.
Filed on a break-up basis — the business is being wound up.
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £0 | £0 | |
| Gross profit | £0 | £0 | |
| Operating profit | −£149 | £74 | ▼ −301% |
| Finance costs | £157 | £0 | |
| Profit before tax | −£149 | £214 | ▼ −170% |
| Net profit | −£66 | £177 | ▼ −137% |
| Cash & balance sheet | |||
| Cash | £224 | £228 | ▼ −2% |
| Net assets | £2,863 | £2,929 | ▼ −2% |
This financial intermediation subsidiary's accounts are no longer prepared on a going-concern basis. The filing is drawn up on a break-up basis ahead of an intended liquidation in the near future. The entity booked zero turnover and a £149 operating loss, with the accounts noting an expectation of no further carried interest income from its private equity vehicles.
Dalata Cardiff Limited [1]
The company operates the Clayton Hotel in central Cardiff and is a subsidiary of the listed hospitality operator Dalata Hotel Group PLC.
Lease drag
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £110.8m | £98.9m | ▲ +12% |
| Gross profit | £66.3m | £59.8m | ▲ +11% |
| Admin expenses | £52.4m | £46m | ▲ +14% |
| Operating profit | £13.8m | £13.8m | ▲ +0% |
| Finance costs | £22.8m | £20.7m | ▲ +10% |
| Profit before tax | −£9m | −£7m | ▼ −29% |
| Net profit | −£7.6m | −£6.8m | ▼ −10% |
| Cash & balance sheet | |||
| Cash | £1.2m | £4.3m | ▼ −73% |
| Net assets | −£52.1m | −£44.5m | ▼ −17% |
| People & pay | |||
| Avg. headcount | 577 | 511 | ▲ +13% |
| Staff cost | £23m | £18.2m | ▲ +26% |
Turnover at the Cardiff hotel operator rose 12% to £110.8m, while operating profit held flat at £13.8m. Below the line, the loss before tax widened to £9.0m as finance costs climbed 10% to £22.8m. The filing attributes this to high interest charges in the early years of recently commenced leases.
M&G Real Estate Limited [2]
Operating as the specialist property management arm of the wider M&G investment group, the company provides global real estate fund and asset management services.
Pricier payroll
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £76.1m | £75.5m | ▲ +1% |
| Admin expenses | £31.9m | £36m | ▼ −11% |
| Operating profit | £44.1m | £39.5m | ▲ +12% |
| Profit before tax | £64.2m | £59.2m | ▲ +8% |
| Net profit | £51.3m | £48.5m | ▲ +6% |
| Cash & balance sheet | |||
| Cash | £6.4m | £7.3m | ▼ −12% |
| Net assets | £69.5m | £74.1m | ▼ −6% |
| Dividends paid | £57.3m | £79m | ▼ −27% |
| People & pay | |||
| Avg. headcount | 143 | 173 | ▼ −17% |
| Staff cost | £32.8m | £30m | ▲ +9% |
| Director pay | £1.9m | £2.4m | ▼ −21% |
| Highest-paid director | £1.2m | £1.4m | ▼ −15% |
Turnover held steady at £76.1m for the property management arm, while operating profit climbed 12% to £44.1m. Notably, average headcount fell 17% to 143, yet total staff costs rose 9% to £32.8m, as overall payroll expenses increased. Profit before tax reached £64.2m, lifted by £18.8m of investment income, alongside a £57.3m dividend.
Bazooka Candy Brands International Ltd [3]
Operating as the international division of US-based The Bazooka Companies, this private entity wholesales interactive sugar confectionery and bubble gum under brands including Ring Pop, Push Pop, and Juicy Drop, and is ultimately backed by private equity firm Apax Partners.
Supply chain squeeze
| Line | FY26 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £56.1m | £68.3m | ▼ −18% |
| Gross profit | £24.2m | £29.7m | ▼ −19% |
| Admin expenses | £18.3m | £21.5m | ▼ −15% |
| Operating profit | £6.7m | £9.1m | ▼ −26% |
| Finance costs | £361k | — | |
| Profit before tax | £6.5m | £9.1m | ▼ −29% |
| Net profit | £4.9m | £6.9m | ▼ −29% |
| Cash & balance sheet | |||
| Cash | £18.4m | £15m | ▲ +22% |
| Net assets | £22.6m | £17.7m | ▲ +28% |
| People & pay | |||
| Avg. headcount | 54 | 52 | ▲ +4% |
| Director pay | £550k | £429k | ▲ +28% |
| Highest-paid director | £550k | £429k | ▲ +28% |
The sweet distributor saw turnover fall 18% to £56.1m, while operating profit decreased to £6.7m. The filing notes that the UK market remained resilient, but global inflation and foreign exchange volatility coincided with the top-line contraction. Post-period, the accounts state that Middle East shipping disruptions have pushed ocean freight and marine insurance costs higher.
Sky Retail Stores Limited [4]
Operating as a wholly-owned subsidiary of Sky UK Limited within the Comcast group, the company runs kiosk-based units and shops across the UK and Ireland to sell and advise on Sky's television, broadband, and mobile products.
Static trading
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £27.7m | £28.8m | ▼ −4% |
| Operating profit | £2.5m | £2.6m | ▼ −4% |
| Profit before tax | £2.5m | £2.6m | ▼ −4% |
| Net profit | £2.5m | £2.6m | ▼ −4% |
| Cash & balance sheet | |||
| Net assets | £35.8m | £33.3m | ▲ +7% |
| People & pay | |||
| Avg. headcount | 484 | 484 | ▲ −0% |
| Staff cost | £24.9m | £25.8m | ▼ −3% |
A broadly static year for the kiosk operator. Turnover dipped modestly to £27.7m, operating profit held at £2.5m, and average headcount remained entirely flat at 484. The primary structural development sits in the notes, which outline Comcast's intention to spin off Sky into a separate publicly traded company.
Domain Registry Services Limited [5]
The company operates as a UK entity within the Identity Digital domain registry group, sharing directorships with related subsidiaries including Donuts (UK) Limited and Internet Computer Bureau.
Margin machine
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £25.3m | £30m | ▼ −16% |
| Gross profit | £22.6m | £27.5m | ▼ −18% |
| Admin expenses | £345k | £1,331 | ▲ +25817% |
| Operating profit | £22.3m | £27.5m | ▼ −19% |
| Finance costs | £6,996 | £26,609 | ▼ −74% |
| Profit before tax | £28.1m | £32.3m | ▼ −13% |
| Net profit | £22.8m | £24.2m | ▼ −6% |
| Cash & balance sheet | |||
| Cash | £992 | £3,961 | ▼ −75% |
| Net assets | £107.3m | £84.5m | ▲ +27% |
| People & pay | |||
| Avg. headcount | 3 | 3 | ▲ −0% |
This three-employee domain registry remains a remarkable margin machine, despite a 16% revenue drop to £25.3m. Operating profit settled at £22.3m, yielding the sort of margin you can nap on. The balance sheet continues to expand, with net assets crossing the hundred-million mark to £107.3m.
A reminder that a three-person payroll is plenty if you own the right domains.
Sources
- Dalata Cardiff Limited
- M&G Real Estate Limited
- Bazooka Candy Brands International Ltd
- Sky Retail Stores Limited
- Domain Registry Services Limited