The Accounts · daily brief
15 September 2026
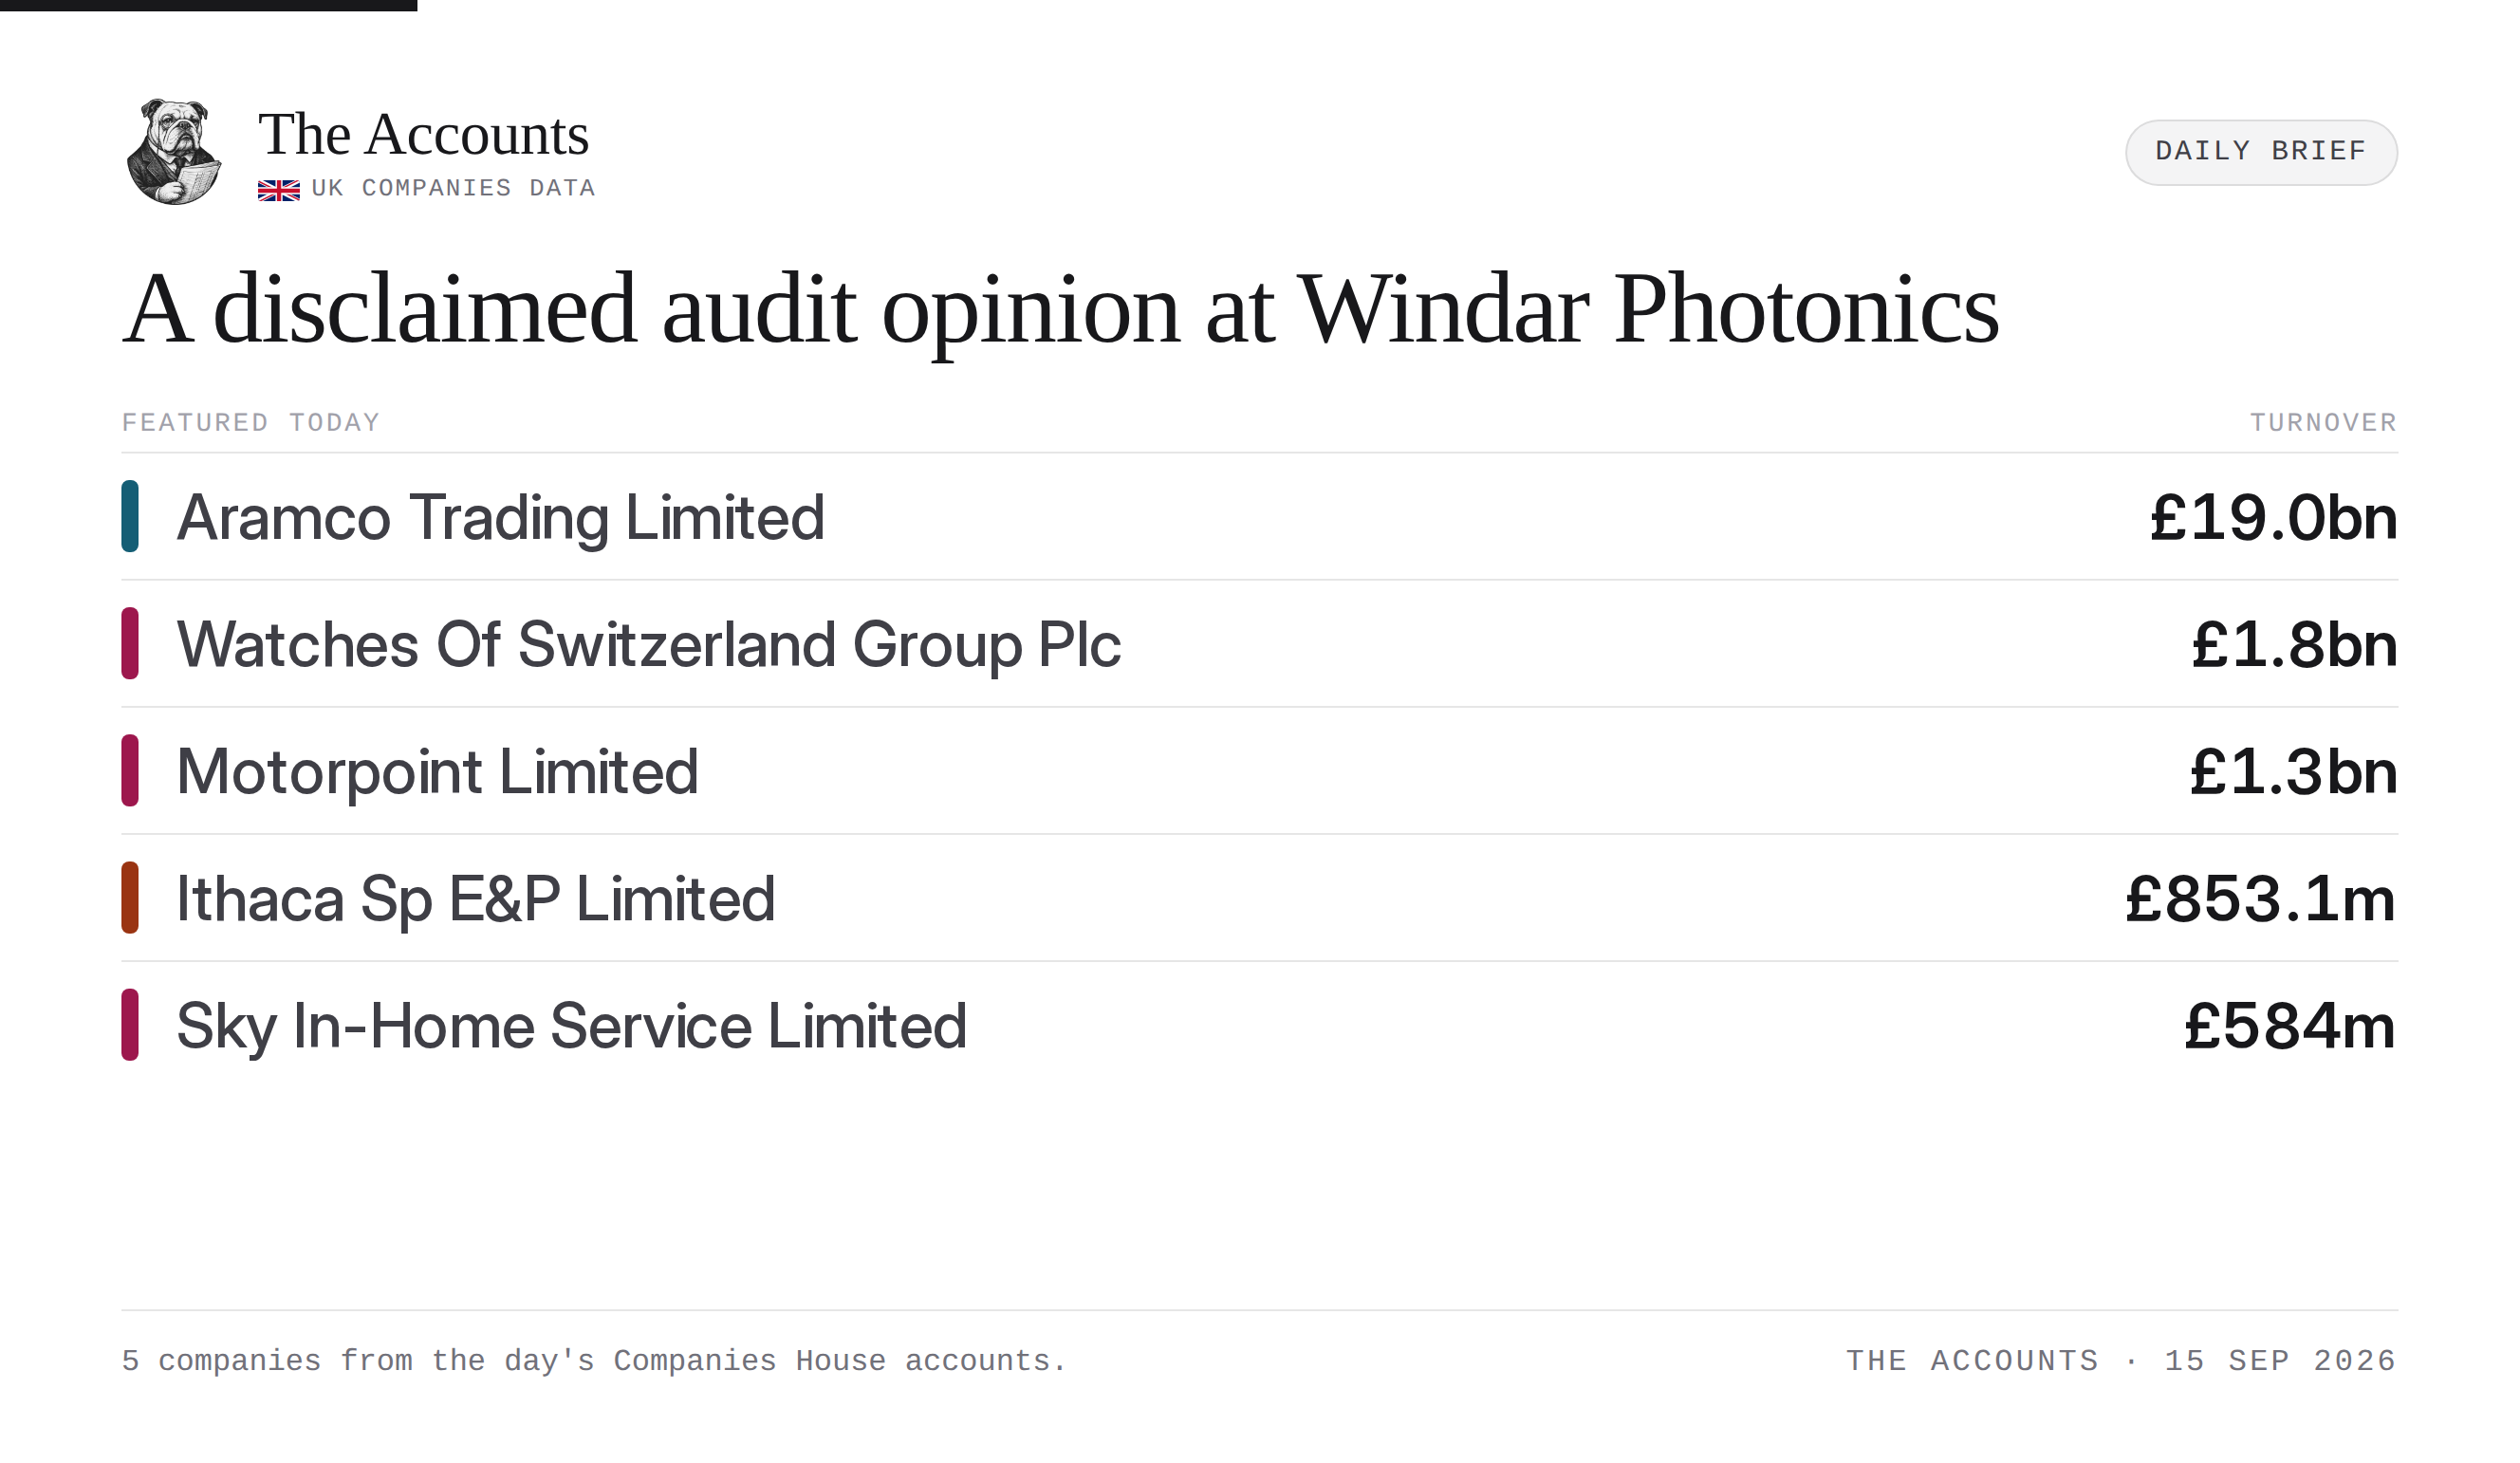
A disclaimed audit opinion at Windar Photonics
The takeaways
- Buzzacott disclaimed its audit opinion on Windar Photonics' accounts alongside a material uncertainty warning
- Watches of Switzerland posted a £133.5m pre-tax profit, aided by price hikes on Swiss watch imports
- Headcount at Sky's in-home installation unit fell 11% as turnover dropped by £76m
Hiring signals · who grew, who shrank
Hiring
- Pb Wholesale U.K. Limited 28 → 43 staff ▲ +54% staff cost +27%
- Pfeifer Drako Limited 57 → 75 staff ▲ +32% staff cost +37%
Cutting
- Kinecx Energy Limited 110 → 68 staff ▼ −38% staff cost −33%
- Ringcentral Uk Ltd 204 → 156 staff ▼ −24% staff cost −23%
Average headcount from the accounts filed yesterday — a look back at last year's payroll, not a live hiring tracker.
Filing of note
Windar Photonics Plc
Listed on the AIM market, the company serves as the ultimate parent of a technology group that develops LiDAR wind sensors and related software to optimise the performance of electricity-generating wind turbines.
Auditor disclaimed an opinion.
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £4.9m | £2.9m | ▲ +69% |
| Gross profit | £2.6m | £1.1m | ▲ +147% |
| Admin expenses | £3.9m | £2.9m | ▲ +33% |
| Operating profit | −£1.3m | −£2.1m | ▲ +38% |
| Finance costs | £819k | £32,032 | ▲ +2456% |
| Profit before tax | −£1.9m | −£2.1m | ▲ +8% |
| Net profit | −£1.6m | −£1.9m | ▲ +15% |
| Cash & balance sheet | |||
| Cash | £3.5m | £6m | ▼ −43% |
| Net assets | £6.3m | £7.5m | ▼ −17% |
| People & pay | |||
| Avg. headcount | 38 | 32 | ▲ +19% |
| Staff cost | £2.1m | £1.7m | ▲ +24% |
| Director pay | £428k | £428k | ▲ +0% |
| Highest-paid director | £182k | £171k | ▲ +6% |
A notable filing comes from this AIM-listed wind sensor group, where auditor Buzzacott entirely disclaimed its opinion on the accounts. While turnover jumped 68% to £4.8m and operating losses narrowed to £1.2m, the disclaimer of opinion is paired with a material uncertainty warning over the group's ability to continue as a going concern. It is a significant audit qualification on a set of numbers that otherwise show top-line momentum.
Aramco Trading Limited [1]
Operating from London, the company acts as the UK commodity trading arm of Saudi Aramco, focusing on the global supply and trading of crude oil, refined petroleum products, and petrochemicals.
Margin expansion
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £19.0bn | £20.5bn | ▼ −7% |
| Gross profit | £205.9m | £170.7m | ▲ +21% |
| Admin expenses | £37.6m | £24.4m | ▲ +54% |
| Operating profit | £168.3m | £146.3m | ▲ +15% |
| Finance costs | £7.4m | £17.8m | ▼ −58% |
| Profit before tax | £213.4m | £132.9m | ▲ +61% |
| Net profit | £160m | £99.7m | ▲ +61% |
| Cash & balance sheet | |||
| Cash | £228.4m | £188.2m | ▲ +21% |
| Dividends paid | −£111.1m | £0 | |
| People & pay | |||
| Avg. headcount | 89 | 78 | ▲ +14% |
| Staff cost | £18.4m | £15.5m | ▲ +19% |
Turnover fell 7% to £18.9bn, but operating profit climbed 15% to £168.3m for the Saudi oil giant's London trading arm. The strategic report notes a volume-trading budget of 752,000 barrels a day, citing geopolitical shifts as a factor in widened margins. A £111.1m dividend was paid to the parent company, up from nothing the year before.
Watches Of Switzerland Group Plc [2]
Listed on the London Stock Exchange, the group is an international luxury watch and jewellery retailer operating multi-brand showrooms and mono-brand boutiques under trading names such as Mappin & Webb, Goldsmiths, and Mayors across the UK, US, and Europe.
Tariff-aided growth
| Line | FY26 | FY25 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £1.8bn | £1.7bn | ▲ +11% |
| Gross profit | £237.2m | £211.2m | ▲ +12% |
| Admin expenses | £58.4m | £43.6m | ▲ +34% |
| Operating profit | £170m | — | |
| Finance costs | £36.5m | £38.1m | ▼ −4% |
| Profit before tax | £133.5m | £75.9m | ▲ +76% |
| Net profit | £99m | £53.8m | ▲ +84% |
| Cash & balance sheet | |||
| Dividends paid | £12.9m | — | |
| People & pay | |||
| Avg. headcount | 2,942 | — | |
| Staff cost | £93.7m | — | |
| Director pay | £1.3m | — | |
Record sales of £1.82bn delivered a £133.5m pre-tax profit for the luxury jeweller, up sharply from £75.9m. The filing notes the top-line growth was aided by price increases from brands reacting to tariffs on Swiss watch imports. The launch of a certified pre-owned Rolex programme continues to feature in the strategic highlights as the group expands its mono-brand footprint.
Motorpoint Limited [3]
The company serves as the principal trading subsidiary of the London-listed Motorpoint Group Plc, operating as an omnichannel retailer of nearly new cars and commercial vehicles across the United Kingdom.
Volume-driven profit
| Line | FY26 | FY25 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £1.3bn | £1.2bn | ▲ +8% |
| Gross profit | £98.9m | £90.8m | ▲ +9% |
| Admin expenses | £81m | £77.9m | ▲ +4% |
| Operating profit | £18m | £13.7m | ▲ +31% |
| Finance costs | £9.6m | £9m | ▲ +7% |
| Profit before tax | £8.4m | £4.7m | ▲ +79% |
| Net profit | £6.3m | £3.8m | ▲ +66% |
| Cash & balance sheet | |||
| Cash | £5.2m | £6.6m | ▼ −21% |
| Net assets | £96.8m | £89.1m | ▲ +9% |
| People & pay | |||
| Avg. headcount | 829 | 791 | ▲ +5% |
| Staff cost | £39.4m | £38.9m | ▲ +1% |
| Director pay | £1.7m | £1.3m | ▲ +31% |
| Highest-paid director | £400k | £400k | ▲ −0% |
The used car retailer pushed turnover up 8% to £1.26bn, lifting operating profit to £18m. The filing attributes the increase to a leaner organisation and a 22.8% two-year volume growth, noted against a challenging used car market. Headcount crept up to 829 during the period, though the resulting wage bill remained largely flat at £33.3m.
Ithaca Sp E&P Limited [4]
Ithaca SP E&P Limited, formerly known as Siccar Point Energy E&P Limited, operates as a North Sea oil and gas exploration and production subsidiary within the listed Ithaca Energy plc group.
Production surge
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £853.1m | £612.9m | ▲ +39% |
| Gross profit | £282.5m | £171m | ▲ +65% |
| Admin expenses | £160k | £267k | ▼ −40% |
| Operating profit | £231k | −£253.5m | ▲ +100% |
| Finance costs | £120.1m | £102.1m | ▲ +18% |
| Profit before tax | £251.4m | −£355.3m | ▲ +171% |
| Net profit | £91.4m | £156.9m | ▼ −42% |
| Cash & balance sheet | |||
| Net assets | £1.3bn | £1.4bn | ▼ −6% |
| People & pay | |||
| Director pay | £160k | £267k | ▼ −40% |
Asset transfers accompanied a 53% surge in production to 15.4m barrels of oil equivalent, lifting turnover to £853m for this North Sea subsidiary. That was enough to push operating profit back into the black at £231k, a stark recovery from the prior year's £253.4m loss. The bottom line was subsequently absorbed by a £342.8m tax charge, though a £1.34bn net asset base provides a substantial buffer.
Sky In-Home Service Limited [5]
Operating as a wholly owned subsidiary of Sky UK Limited and ultimately controlled by Comcast, the company manages the supply chain, equipment distribution, and field engineering force for the group's satellite television, broadband, and telephony installations.
Contracting operations
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £584m | £660m | ▼ −12% |
| Operating profit | £53m | £60m | ▼ −12% |
| Finance costs | £48m | £66m | ▼ −27% |
| Profit before tax | £5m | −£6m | ▲ +183% |
| Net profit | £4m | £14m | ▼ −71% |
| People & pay | |||
| Avg. headcount | 2,155 | 2,437 | ▼ −12% |
| Staff cost | £103m | £126m | ▼ −18% |
Turnover at the broadcaster's installation and supply chain arm fell 11% to £584m. Average headcount fell by nearly 300 staff during the period, bringing the total down to 2,155 and reducing the total staff cost bill to £103m. Operating profit slipped to £53m alongside the shrinking sales, while a substantial £48m finance cost left just £5m on the pre-tax line.
A reminder that no matter how fast the top line is spinning, it means little if the auditor disclaims an opinion.
Sources
- Aramco Trading Limited
- Watches Of Switzerland Group Plc
- Motorpoint Limited
- Ithaca Sp E&P Limited
- Sky In-Home Service Limited