The Accounts · daily brief
6 October 2026
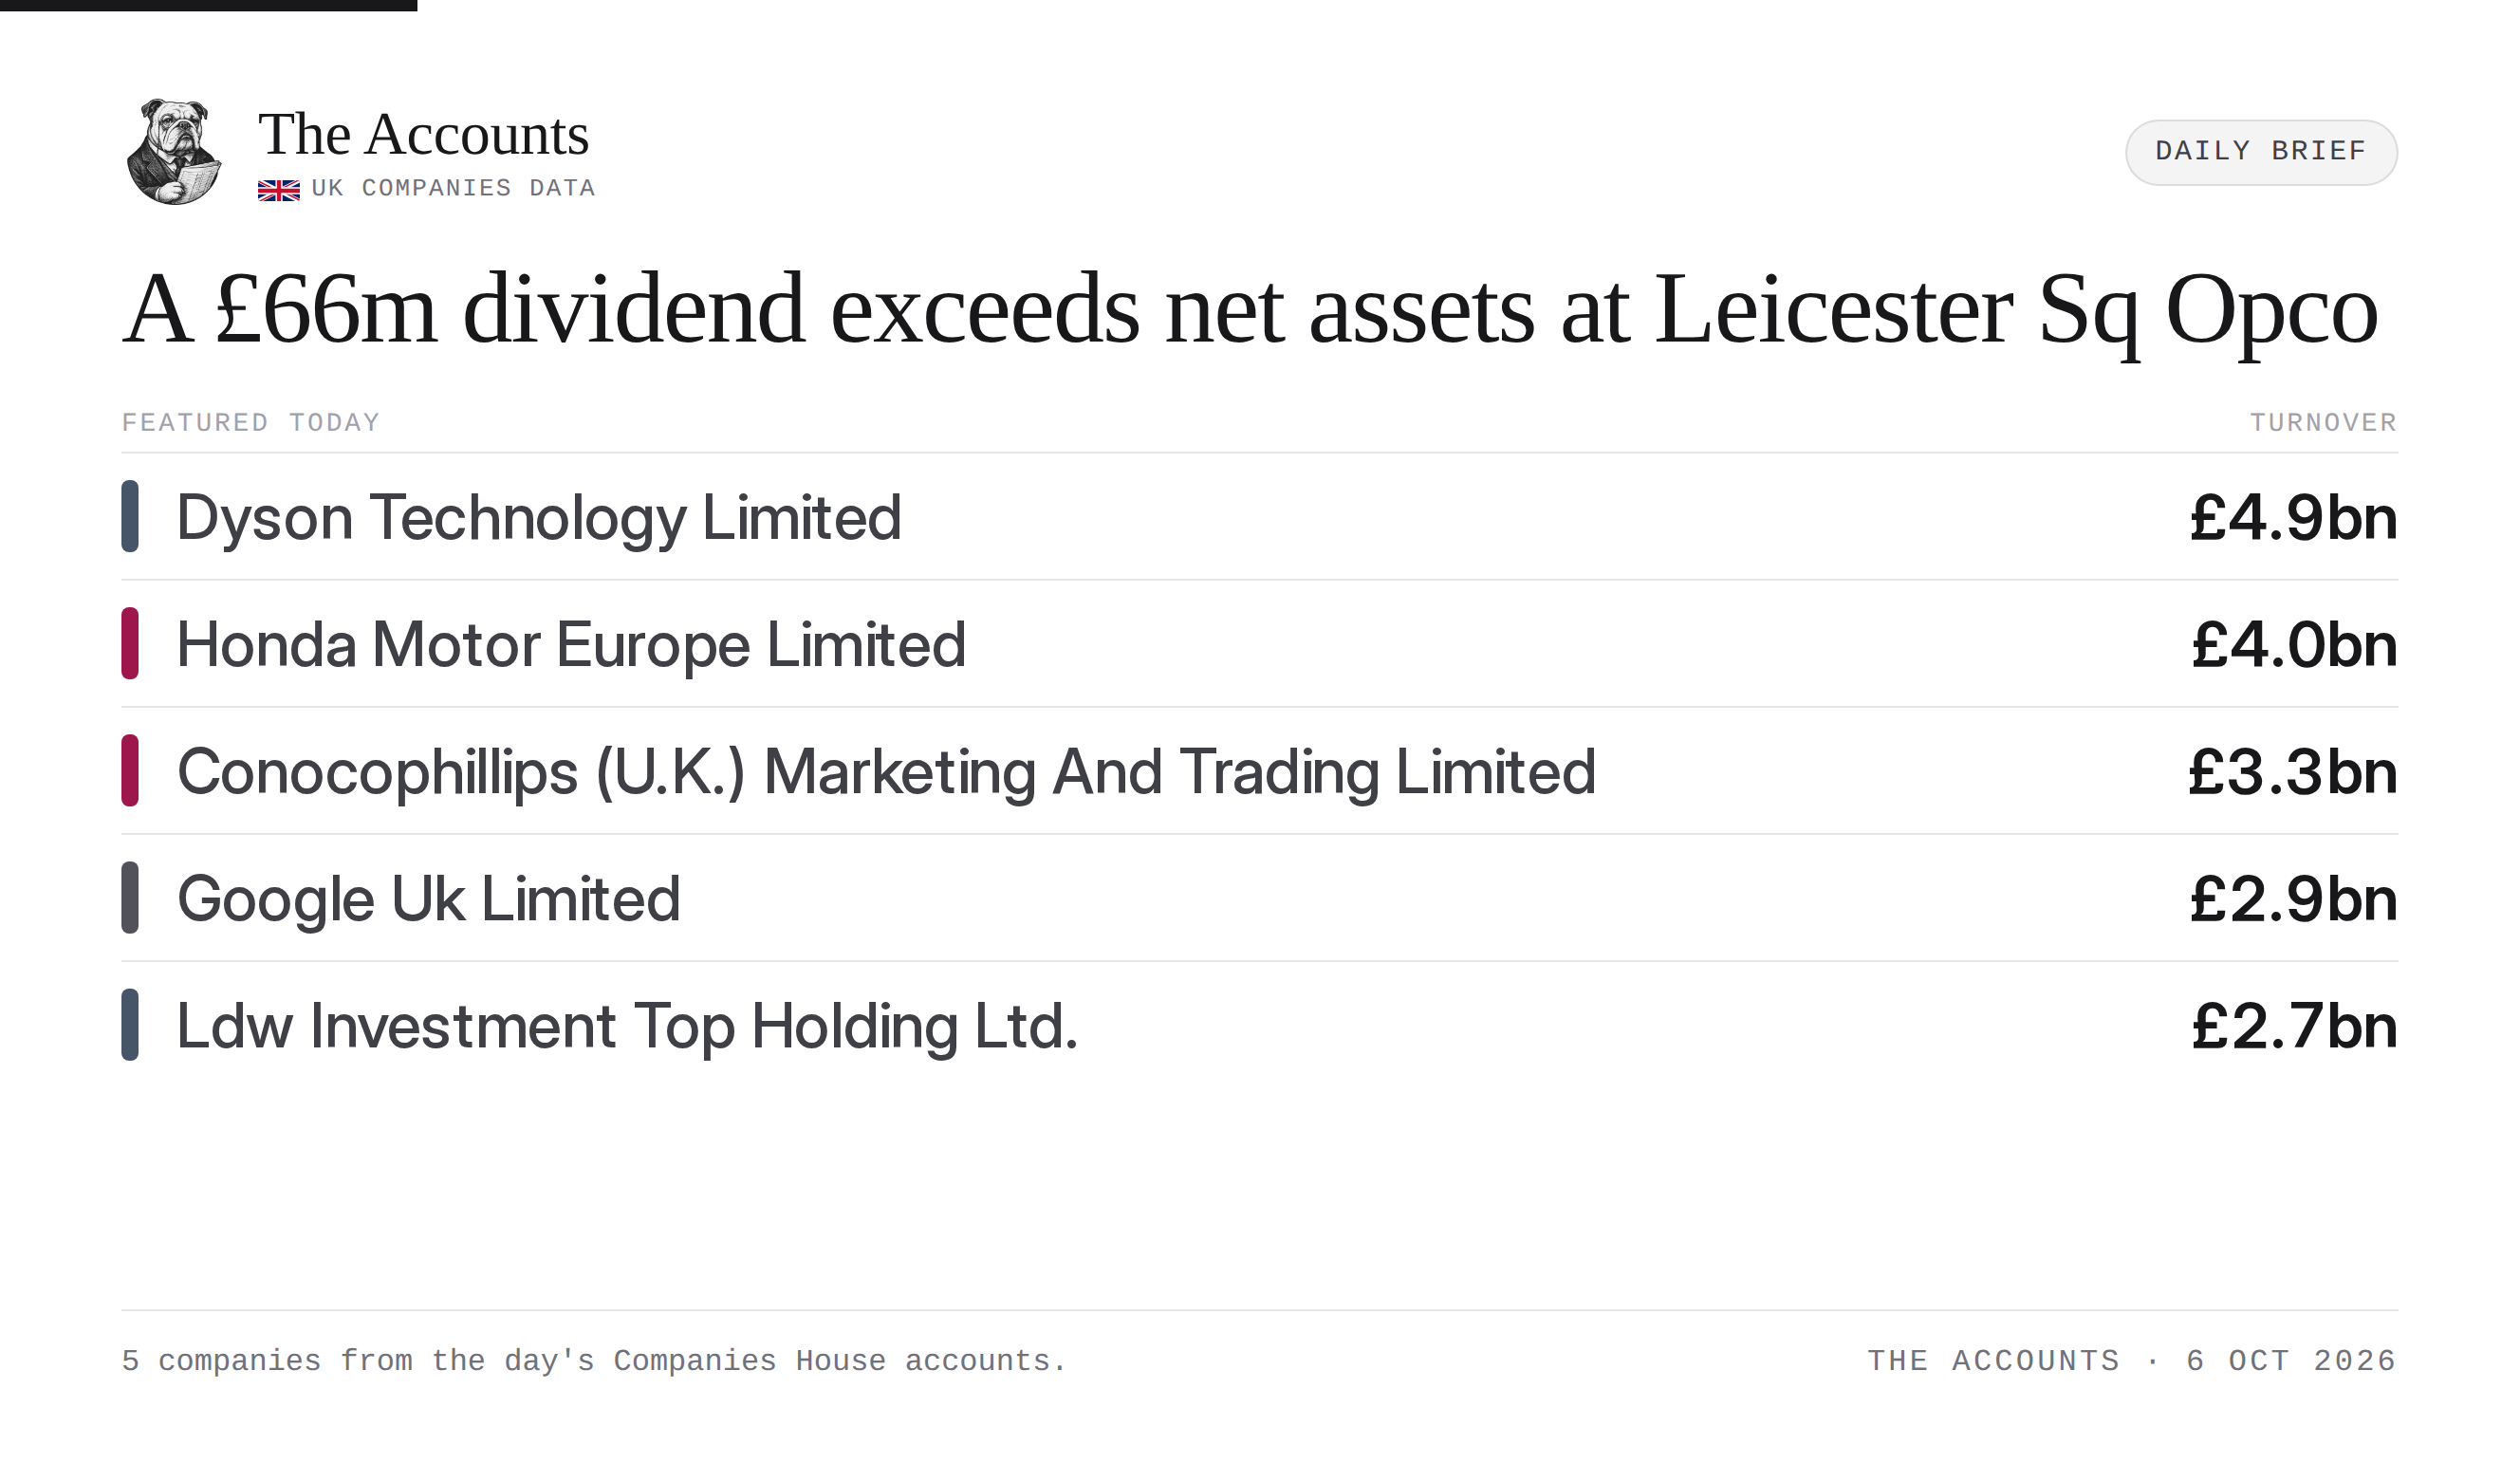
A £66m dividend exceeds net assets at Leicester Sq Opco
The takeaways
- Honda Motor Europe swung to an £80.1m operating loss as the filing cited shipping delays
- Dyson's operating profit halved to £158.4m while a reorganisation reduced headcount by 385
- Google UK headcount fell by 5% while total staff costs rose 8.3% to £2.42bn
Hiring signals · who grew, who shrank
Hiring
- Resultscx Uk Limited 1,857 → 6,558 staff ▲ +253% staff cost +241%
- Shein Distribution Uk Limited 33 → 91 staff ▲ +176% staff cost +143%
Cutting
- Red Bull Powertrains Limited 135 → 44 staff ▼ −67% staff cost −56% material-uncertainty note
- Bae Systems (Oman) Limited 71 → 27 staff ▼ −62% staff cost −36%
Average headcount from the accounts filed yesterday — a look back at last year's payroll, not a live hiring tracker.
Filing of note
Leicester Sq Opco Ltd
Formerly known as Edwardian Hampshire Hotels Ltd, the company operates a hotel in London's Leicester Square and is a subsidiary of Ferrado UK Limited.
Paid a £66.4m dividend on £2.9m of equity.
| Line | FY24 | FY23 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £14.2m | £16.1m | ▼ −12% |
| Gross profit | £8.6m | £11.1m | ▼ −22% |
| Admin expenses | £4.3m | £5.4m | ▼ −20% |
| Operating profit | £4.3m | £5.7m | ▼ −25% |
| Finance costs | £2.5m | £1.8m | ▲ +36% |
| Profit before tax | £512k | £4.6m | ▼ −89% |
| Net profit | £31,356 | £4.2m | ▼ −99% |
| Cash & balance sheet | |||
| Cash | £3.1m | £1.2m | ▲ +171% |
| Net assets | £2.9m | £65.3m | ▼ −96% |
| Dividends paid | −£66.4m | — | |
| People & pay | |||
| Avg. headcount | 82 | 107 | ▼ −23% |
| Staff cost | £2.8m | £4m | ▼ −29% |
A notable filing comes from this Leicester Square hotel operator, which paid out a £66.4m dividend that exceeded its remaining £2.9m of equity. Core trading was somewhat muted, with turnover falling 11% to £14.2m. Operating profit slipped to £4.2m, while the filing reported no significant post-year-end events alongside the capital distribution.
Dyson Technology Limited [1]
Operating via dyson.co.uk, the privately held company serves as a primary UK engineering, research, and manufacturing subsidiary of the Singapore-headquartered Dyson Group (ultimately Dyson Holdings Pte. Limited), developing the brand's household appliances such as vacuum cleaners, fans, and hair care products.
Restructuring drag
| Line | FY24 | FY23 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £4.9bn | £5.1bn | ▼ −4% |
| Gross profit | £942.4m | £1.1bn | ▼ −18% |
| Admin expenses | £768.5m | £794.1m | ▼ −3% |
| Operating profit | £158.4m | £295.1m | ▼ −46% |
| Finance costs | £50.5m | £44.8m | ▲ +13% |
| Profit before tax | £225.1m | £335.9m | ▼ −33% |
| Net profit | £173.1m | £269.4m | ▼ −36% |
| Cash & balance sheet | |||
| Cash | £2m | £0 | |
| Net assets | £301m | £327.9m | ▼ −8% |
| Dividends paid | −£200m | −£650m | ▲ +69% |
| People & pay | |||
| Avg. headcount | 2,929 | 3,314 | ▼ −12% |
| Staff cost | £208.5m | £249.7m | ▼ −16% |
| Director pay | £100k | £100k | ▲ −0% |
Operating profit nearly halved to £158.4m as turnover dipped slightly to £4.88bn at the engineering subsidiary. The filing notes a late-year reorganisation reduced average headcount by 385 employees. The bottom line was supported by £117.2m in finance income, while the dividend payout was reduced to £200m.
Honda Motor Europe Limited [2]
Operating as the European division of the Japanese automotive manufacturer Honda Motor Co. Ltd, the company oversees the wholesale, distribution, and sale of new and used cars, motorcycles, and related parts across the region.
Supply chain toll
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £4.0bn | £4.5bn | ▼ −12% |
| Gross profit | £380.4m | £510.5m | ▼ −25% |
| Admin expenses | £265.1m | £252.2m | ▲ +5% |
| Operating profit | −£80.2m | £48.5m | ▼ −265% |
| Finance costs | £107.6m | £87.1m | ▲ +23% |
| Profit before tax | −£204m | −£29.9m | ▼ −583% |
| Net profit | −£209.9m | £7.3m | ▼ −2974% |
| Cash & balance sheet | |||
| Cash | £37.2m | £22.5m | ▲ +65% |
| Net assets | −£798.2m | −£595m | ▼ −34% |
| People & pay | |||
| Avg. headcount | 1,281 | 1,266 | ▲ +1% |
| Staff cost | £139.9m | £119.1m | ▲ +17% |
| Director pay | £2.1m | £1.6m | ▲ +31% |
| Highest-paid director | £682k | £563k | ▲ +21% |
Turnover fell 12% to £3.96bn, accompanying an £80.1m operating loss at the European arm of the Japanese automaker. The filing cites geopolitical issues and global events for continued shipping challenges. Below the line, £107.5m in finance costs pushed the pre-tax loss to £203.9m, alongside a material uncertainty note on going concern.
Conocophillips (U.K.) Marketing And Trading Limited [3]
This entity serves as the European commercial marketing and trading arm for crude oil, natural gas liquids, and natural gas on behalf of the NYSE-listed global energy corporation ConocoPhillips (conocophillips.com).
Zero-staff trading
| Line | FY24 | FY23 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £3.3bn | £3.4bn | ▼ −4% |
| Operating profit | −£26.9m | −£15.3m | ▼ −76% |
| Finance costs | £3.7m | £3.5m | ▲ +7% |
| Profit before tax | −£17.3m | £63,000 | ▼ −27530% |
| Net profit | −£13m | £21,000 | ▼ −62133% |
| Cash & balance sheet | |||
| Cash | £134.5m | £154.7m | ▼ −13% |
| Net assets | £110.2m | £121.7m | ▼ −9% |
| People & pay | |||
| Avg. headcount | 0 | 0 | |
| Staff cost | £0 | £0 | |
| Director pay | £905k | £1.2m | ▼ −25% |
| Highest-paid director | £481k | £397k | ▲ +21% |
A capital-light passthrough that booked £3.27bn in turnover without a single employee on the payroll. Operating losses widened to £26.9m at the European trading arm. Three ten-year gas sales contracts were signed during the year, and the entity remains a going concern supported by a letter from its parent.
Google Uk Limited [4]
Operating as the British subsidiary of the global technology conglomerate Alphabet Inc., the company provides marketing, research and development, and business support services for the wider Google group (google.co.uk).
Rising payroll
| Line | FY24 | FY23 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £2.9bn | £2.8bn | ▲ +3% |
| Admin expenses | £2.3bn | £2.3bn | ▲ +2% |
| Operating profit | £563.6m | £518.3m | ▲ +9% |
| Finance costs | £29.6m | £31.5m | ▼ −6% |
| Profit before tax | £549.7m | £502.4m | ▲ +9% |
| Net profit | £403.4m | £373.9m | ▲ +8% |
| Cash & balance sheet | |||
| Net assets | £2.0bn | £1.7bn | ▲ +17% |
| People & pay | |||
| Avg. headcount | 7,029 | 7,422 | ▼ −5% |
| Staff cost | £2.4bn | £2.2bn | ▲ +8% |
| Director pay | £0 | £0 | |
The search giant's British arm saw operating profit rise 8.7% to £563.6m while average headcount fell by 5%. The lower headcount coincided with an increase in the overall payroll. Total staff costs rose 8.3% to £2.42bn, moving the average staff cost per employee significantly higher.
Ldw Investment Top Holding Ltd. [5]
Now known as Windoria Investment Top Holding Ltd, the company serves as the ultimate parent for Windoria, a private-label food manufacturing group formed through the merger of US-based Winland Foods and Italy-based La Doria, backed by private equity firm Investindustrial.
Debt-heavy growth
| Line | FY24 | FY23 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £2.7bn | £2.3bn | ▲ +17% |
| Gross profit | £467.2m | £372.3m | ▲ +25% |
| Admin expenses | £149.1m | £123.4m | ▲ +21% |
| Operating profit | £137.2m | £70m | ▲ +96% |
| Finance costs | £143.2m | £74.8m | ▲ +91% |
| Profit before tax | £4.8m | £4.8m | ▲ +2% |
| Net profit | £5.7m | £2.9m | ▲ +95% |
| Cash & balance sheet | |||
| Cash | £109.3m | £200.6m | ▼ −46% |
| Net assets | £464.4m | £633.5m | ▼ −27% |
| Dividends paid | −£171.7m | −£2m | ▼ −8646% |
| People & pay | |||
| Avg. headcount | 3,976 | 3,597 | ▲ +11% |
| Staff cost | £333.5m | £186.4m | ▲ +79% |
| Director pay | £4.8m | — | |
| Highest-paid director | £2.3m | — | |
An acquisitive year for the private-equity-backed food group saw turnover rise 17% to £2.73bn. Operating profit nearly doubled to £137.2m following the purchase of Philadelphia Macaroni Company and a string of other assets. However, the debt associated with these additions resulted in £143.2m of finance costs, largely offsetting the profit before tax.
A dividend twenty-two times the size of net assets is certainly worth a raised eyebrow, but then again, it is Leicester Square.
Sources
- Dyson Technology Limited
- Honda Motor Europe Limited
- Conocophillips (U.K.) Marketing And Trading Limited
- Google Uk Limited
- Ldw Investment Top Holding Ltd.