The Accounts · daily brief
8 October 2026
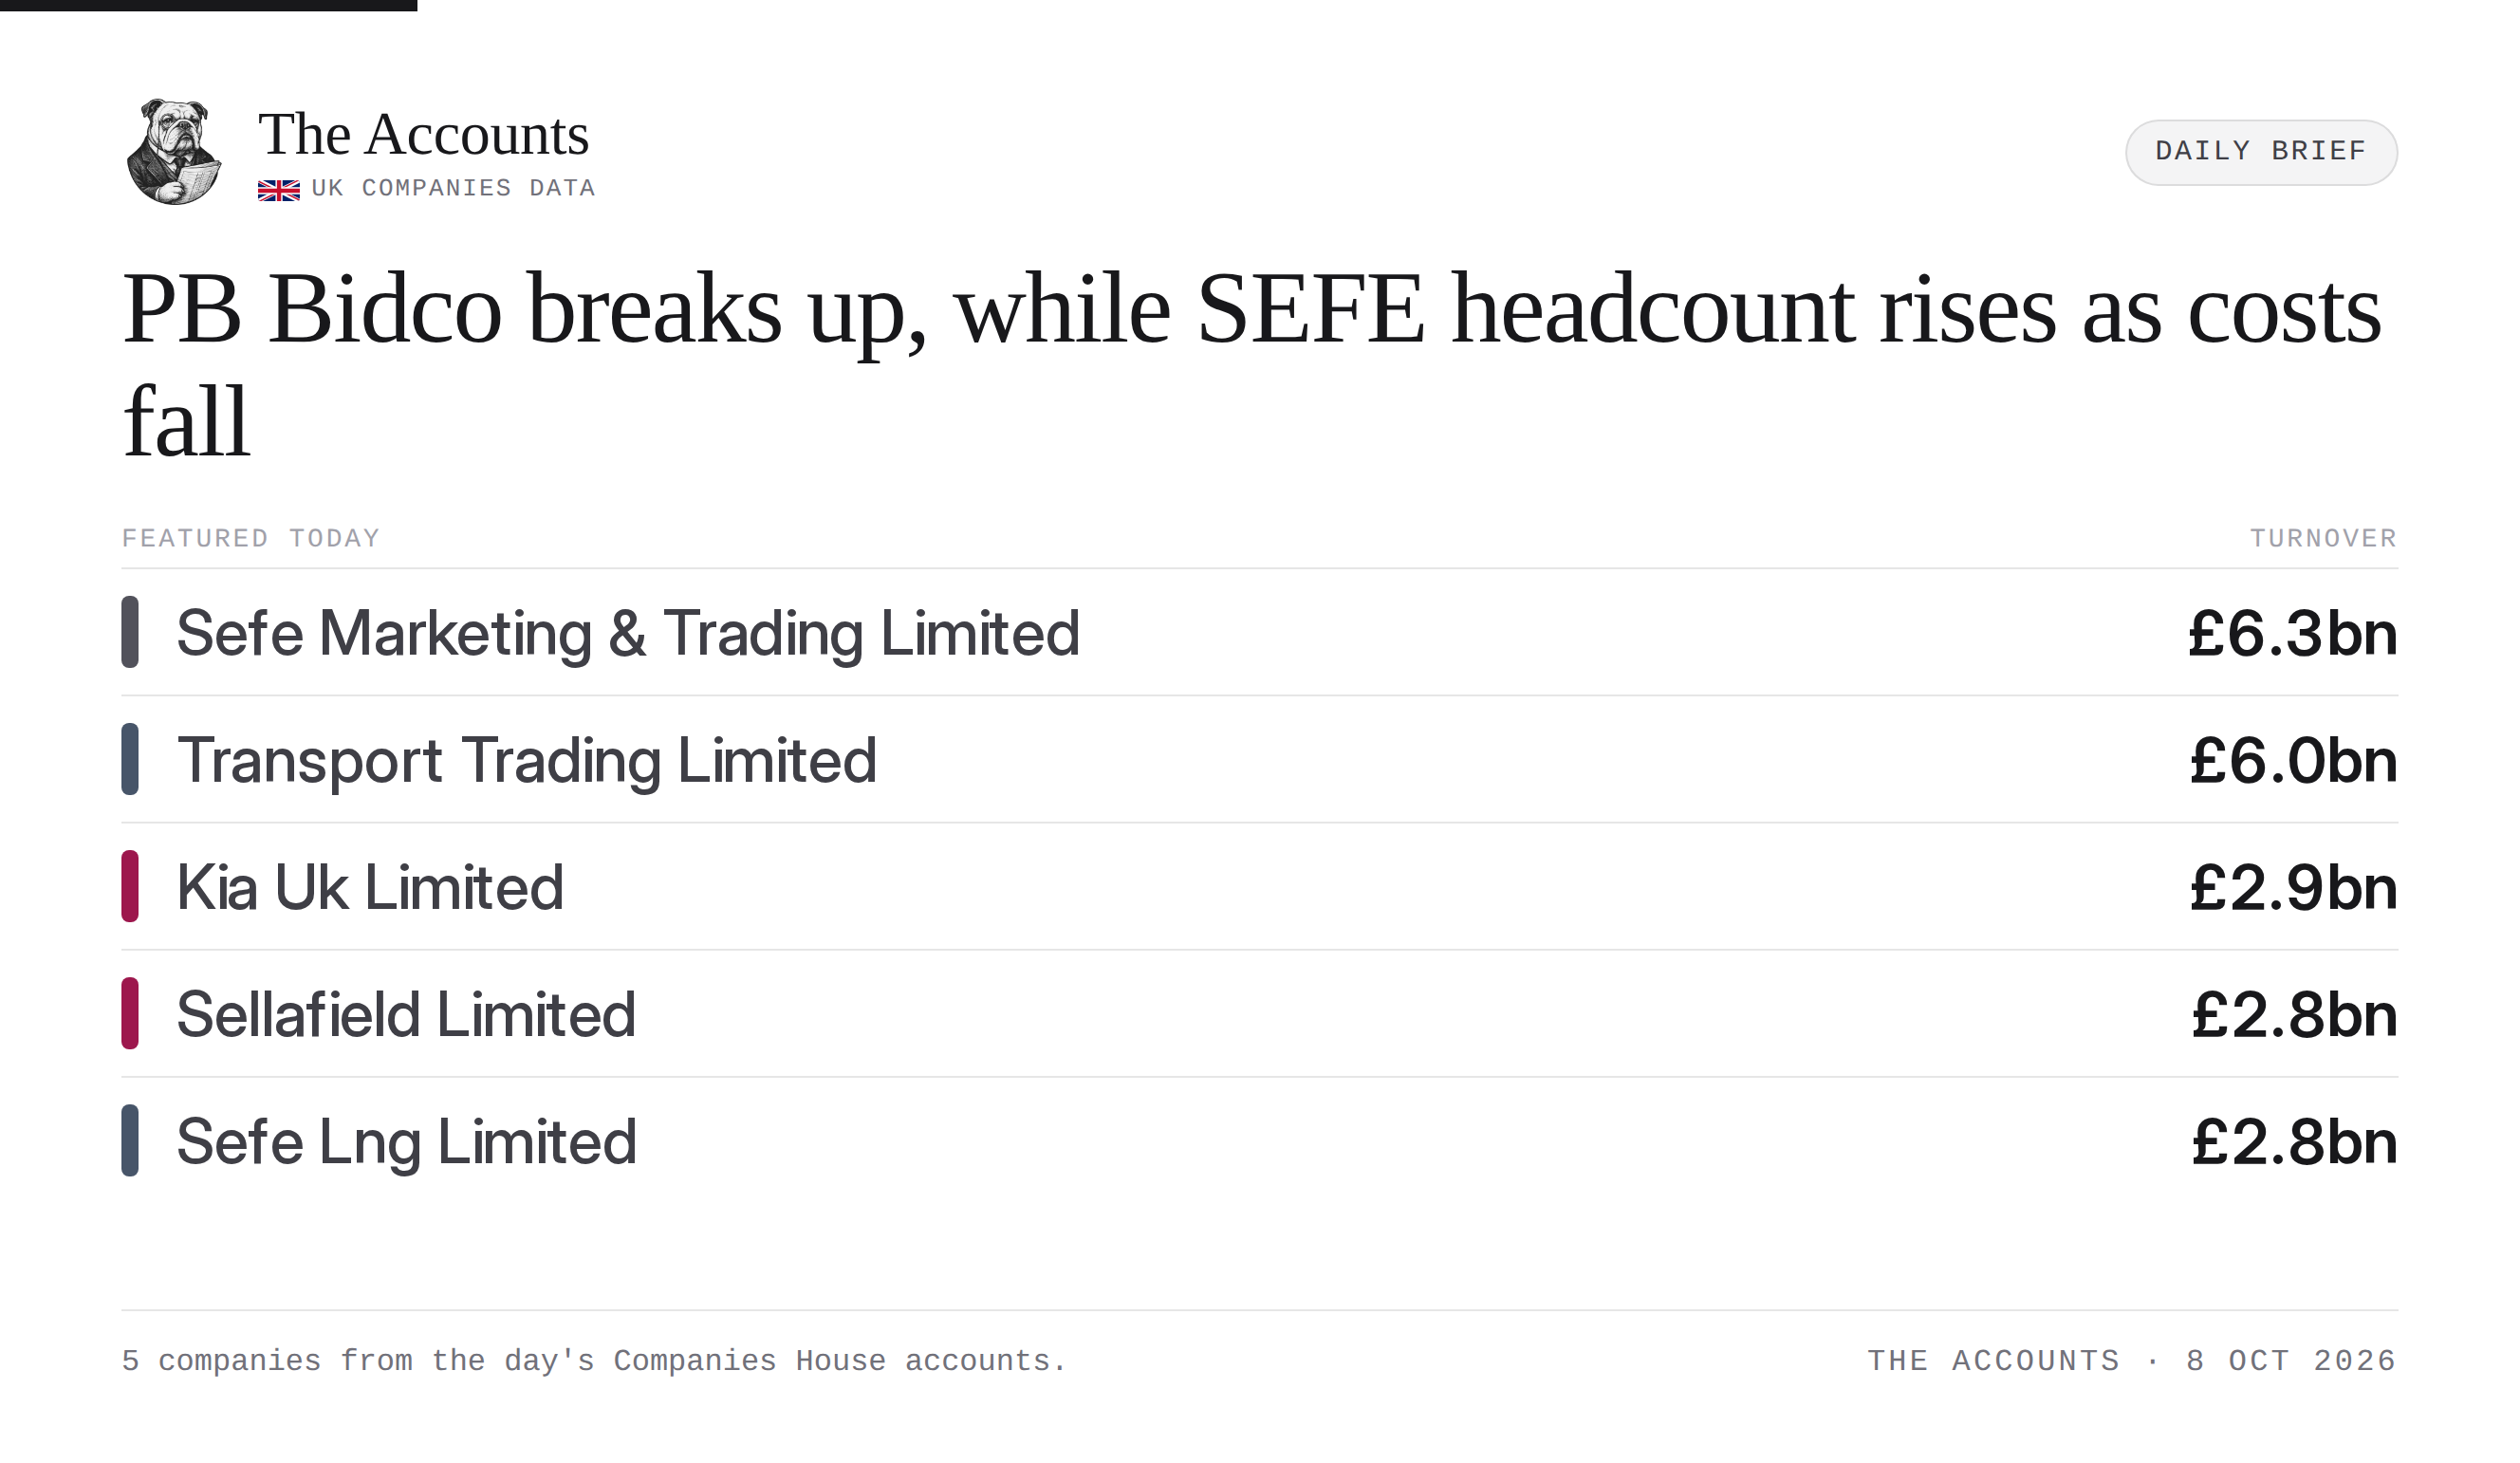
PB Bidco breaks up, while SEFE headcount rises as costs fall
The takeaways
- PB Bidco filed on a break-up basis as its US parent Roper Technologies simplifies the holding structure
- Sellafield runs a pure pass-through model, breaking exactly even while disclosing a nuclear security fine
- SEFE Marketing & Trading saw headcount rise by 100 while total staff costs fell by 14%
Hiring signals · who grew, who shrank
Hiring
- Lonestar Fasteners Hydrobolt Limited 214 → 404 staff ▲ +89% staff cost +84%
- Primevigilance Limited 57 → 99 staff ▲ +74% staff cost +6%
Cutting
- Edrington Distillers Limited 769 → 535 staff ▼ −30% staff cost −36%
- Graham & Brown Limited 386 → 271 staff ▼ −30% staff cost −23%
Average headcount from the accounts filed yesterday — a look back at last year's payroll, not a live hiring tracker.
Filing of note
Pb Bidco Limited
PB Bidco Limited is a UK-based software development holding company that operates as an indirect subsidiary of the American diversified technology group Roper Technologies Inc.
Filed on a break-up (non-going-concern) basis.
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Operating profit | £1.3m | −£1.1m | ▲ +215% |
| Profit before tax | £5.6m | £59.3m | ▼ −91% |
| Net profit | £5.6m | £59.3m | ▼ −91% |
| Cash & balance sheet | |||
| Cash | £4.4m | £3.3m | ▲ +34% |
| Net assets | £88.7m | £83.1m | ▲ +7% |
| People & pay | |||
| Avg. headcount | 3 | 3 | ▲ −0% |
Filed on a break-up (non-going-concern) basis. As part of a simplification process by its US parent Roper Technologies, this software holding company is being wound up. The accounts are purely administrative, with last year's net profit almost entirely attributable to an investment income line that did not recur.
Sefe Marketing & Trading Limited [1]
Operating via sefe-mt.com, the unlisted entity, formerly Gazprom Marketing & Trading Limited, is an energy trading and supply business acting as a subsidiary of the German state-owned group SEFE Securing Energy for Europe GmbH (previously Gazprom Germania).
Staff costs fall
| Line | FY24 | FY23 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £6.3bn | £5.4bn | ▲ +17% |
| Gross profit | £282.9m | £258.5m | ▲ +9% |
| Admin expenses | £447.2m | £393.1m | ▲ +14% |
| Operating profit | £287.8m | £455.7m | ▼ −37% |
| Finance costs | £107.4m | £92.7m | ▲ +16% |
| Profit before tax | £214.1m | £425.8m | ▼ −50% |
| Net profit | £199.4m | £351.3m | ▼ −43% |
| Cash & balance sheet | |||
| Cash | £49.8m | £111.7m | ▼ −55% |
| Net assets | £1.5bn | £1.8bn | ▼ −15% |
| People & pay | |||
| Avg. headcount | 849 | 749 | ▲ +13% |
| Staff cost | £200.5m | £234.4m | ▼ −14% |
| Director pay | £4.1m | £5.3m | ▼ −22% |
| Highest-paid director | £4.1m | £5.3m | ▼ −23% |
The German state-owned energy trader formerly known as Gazprom M&T saw turnover rise, but operating profit fell by more than a third. Average headcount rose by exactly 100 during the period while the total wage bill simultaneously contracted by 14%. The filing notes the business performed in line with expectations, continuing to stabilise after the European energy crisis.
Transport Trading Limited [2]
Transport Trading Limited is the principal holding company for the operating transport and property subsidiaries of Transport for London, overseeing the capital's public transit networks and real estate portfolio via tfl.gov.uk.
Static losses
| Line | FY26 | FY25 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £6.0bn | £5.8bn | ▲ +4% |
| Operating profit | −£1.4bn | −£1.4bn | ▼ −1% |
| Finance costs | £576.4m | £553.5m | ▲ +4% |
| Profit before tax | −£548.7m | −£505.6m | ▼ −9% |
| Net profit | −£525.6m | −£473.2m | ▼ −11% |
| Cash & balance sheet | |||
| Cash | £139.6m | £136.5m | ▲ +2% |
| Net assets | £12.6bn | £13.1bn | ▼ −4% |
| People & pay | |||
| Avg. headcount | 18,614 | 18,582 | ▲ +0% |
| Staff cost | £1.6bn | £1.6bn | ▼ −1% |
| Director pay | £2.5m | £2.4m | ▲ +3% |
| Highest-paid director | £636k | £639k | ▼ −1% |
The principal holding company for TfL's transport network saw fares and grants lift turnover, though a substantial operating loss remained. The cost base was broadly static: a vast wage bill for over 18,000 staff barely moved an inch year-on-year. The going concern basis is supported by the stated expectation of uninterrupted grant funding through to 2028.
Kia Uk Limited [3]
Operating via kia.com/uk, the company acts as the British sales and distribution arm for the South Korean automotive manufacturer Kia Corporation, a subsidiary of the Hyundai Motor Group, supplying new passenger cars, light commercial vehicles, and replacement parts to the domestic market.
Margin narrowed
| Line | FY24 | FY23 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £2.9bn | £2.7bn | ▲ +6% |
| Gross profit | £181.7m | £202.3m | ▼ −10% |
| Admin expenses | £48.2m | £42.7m | ▲ +13% |
| Operating profit | £46.1m | £59.3m | ▼ −22% |
| Finance costs | £2.9m | £2.1m | ▲ +38% |
| Profit before tax | £54.2m | £67.9m | ▼ −20% |
| Net profit | £41.8m | £53.3m | ▼ −22% |
| Cash & balance sheet | |||
| Cash | £21.9m | £14.2m | ▲ +54% |
| Net assets | £276.3m | £234.7m | ▲ +18% |
| People & pay | |||
| Avg. headcount | 265 | 258 | ▲ +3% |
| Staff cost | £20.7m | £19m | ▲ +9% |
| Director pay | £1.2m | £1.1m | ▲ +2% |
| Highest-paid director | £723k | £599k | ▲ +21% |
A 5% rise in turnover for the South Korean marque's British sales arm did not translate to the bottom line. Operating profit dropped 22% as distribution costs and administrative expenses expanded alongside a narrowing margin, though the filing projects sufficient liquidity to 2026 based on expected customer demand.
Sellafield Limited [4]
Formerly British Nuclear Fuels plc, the entity is a state-controlled site licence company operating as a direct subsidiary of the UK government's Nuclear Decommissioning Authority to manage the remediation, clean-up, and safe waste storage at the Cumbrian nuclear facility.
Pass-through model
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £2.8bn | £2.7bn | ▲ +6% |
| Admin expenses | £2.8bn | £2.7bn | ▲ +6% |
| Operating profit | £4m | — | |
| Finance costs | £1m | — | |
| Profit before tax | £4m | — | |
| Net profit | £0 | £0 | |
| Cash & balance sheet | |||
| Cash | £4m | £6m | ▼ −33% |
| Net assets | £0 | £0 | |
| People & pay | |||
| Avg. headcount | 11,653 | 11,038 | ▲ +6% |
| Staff cost | £952m | £897m | ▲ +6% |
| Director pay | £969k | £1.2m | ▼ −17% |
| Highest-paid director | £479k | £349k | ▲ +38% |
The state-controlled nuclear decommissioning site runs on a pure pass-through model, matching its entire revenue against administrative expenses to break exactly even. A notable disclosure in an otherwise perfectly balanced ledger is a £332k fine for past nuclear security compliance failures, though the filing notes public safety was never compromised.
Sefe Lng Limited [5]
SEFE LNG Limited, formerly Gazprom Global LNG Limited, provides liquefied natural gas business support services as a subsidiary of SEFE Marketing & Trading Limited, part of the Securing Energy for Europe (SEFE) group.
One-off skewed
| Line | FY24 | FY23 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £2.8bn | £2.0bn | ▲ +35% |
| Gross profit | £147.9m | £104.5m | ▲ +42% |
| Admin expenses | £28m | £30.4m | ▼ −8% |
| Operating profit | £162.9m | £79.9m | ▲ +104% |
| Finance costs | £26.1m | £35.9m | ▼ −27% |
| Profit before tax | £138.1m | £45.6m | ▲ +203% |
| Net profit | £105.1m | £44.3m | ▲ +137% |
| Cash & balance sheet | |||
| Net assets | −£179.7m | −£148.2m | ▼ −21% |
| Dividends paid | £0 | £0 | |
| People & pay | |||
| Avg. headcount | 19 | 18 | ▲ +6% |
| Staff cost | £26.4m | £28.8m | ▼ −8% |
A record 132 cargo deliveries accompanied a 35% rise in turnover for the SEFE group's LNG arm. Statutory operating profit doubled, but the raw year-on-year comparison is skewed by a £108.3m addition of other operating income this year against a £124.3m charge in the prior period. Excluding those items, underlying trading profit grew at a steadier clip.
A multi-billion pound revenue line that yields absolutely nothing for the bottom line is the sort of financial asceticism that makes a bulldog weep.
Sources
- Sefe Marketing & Trading Limited
- Transport Trading Limited
- Kia Uk Limited
- Sellafield Limited
- Sefe Lng Limited