The Accounts · daily brief
13 October 2026
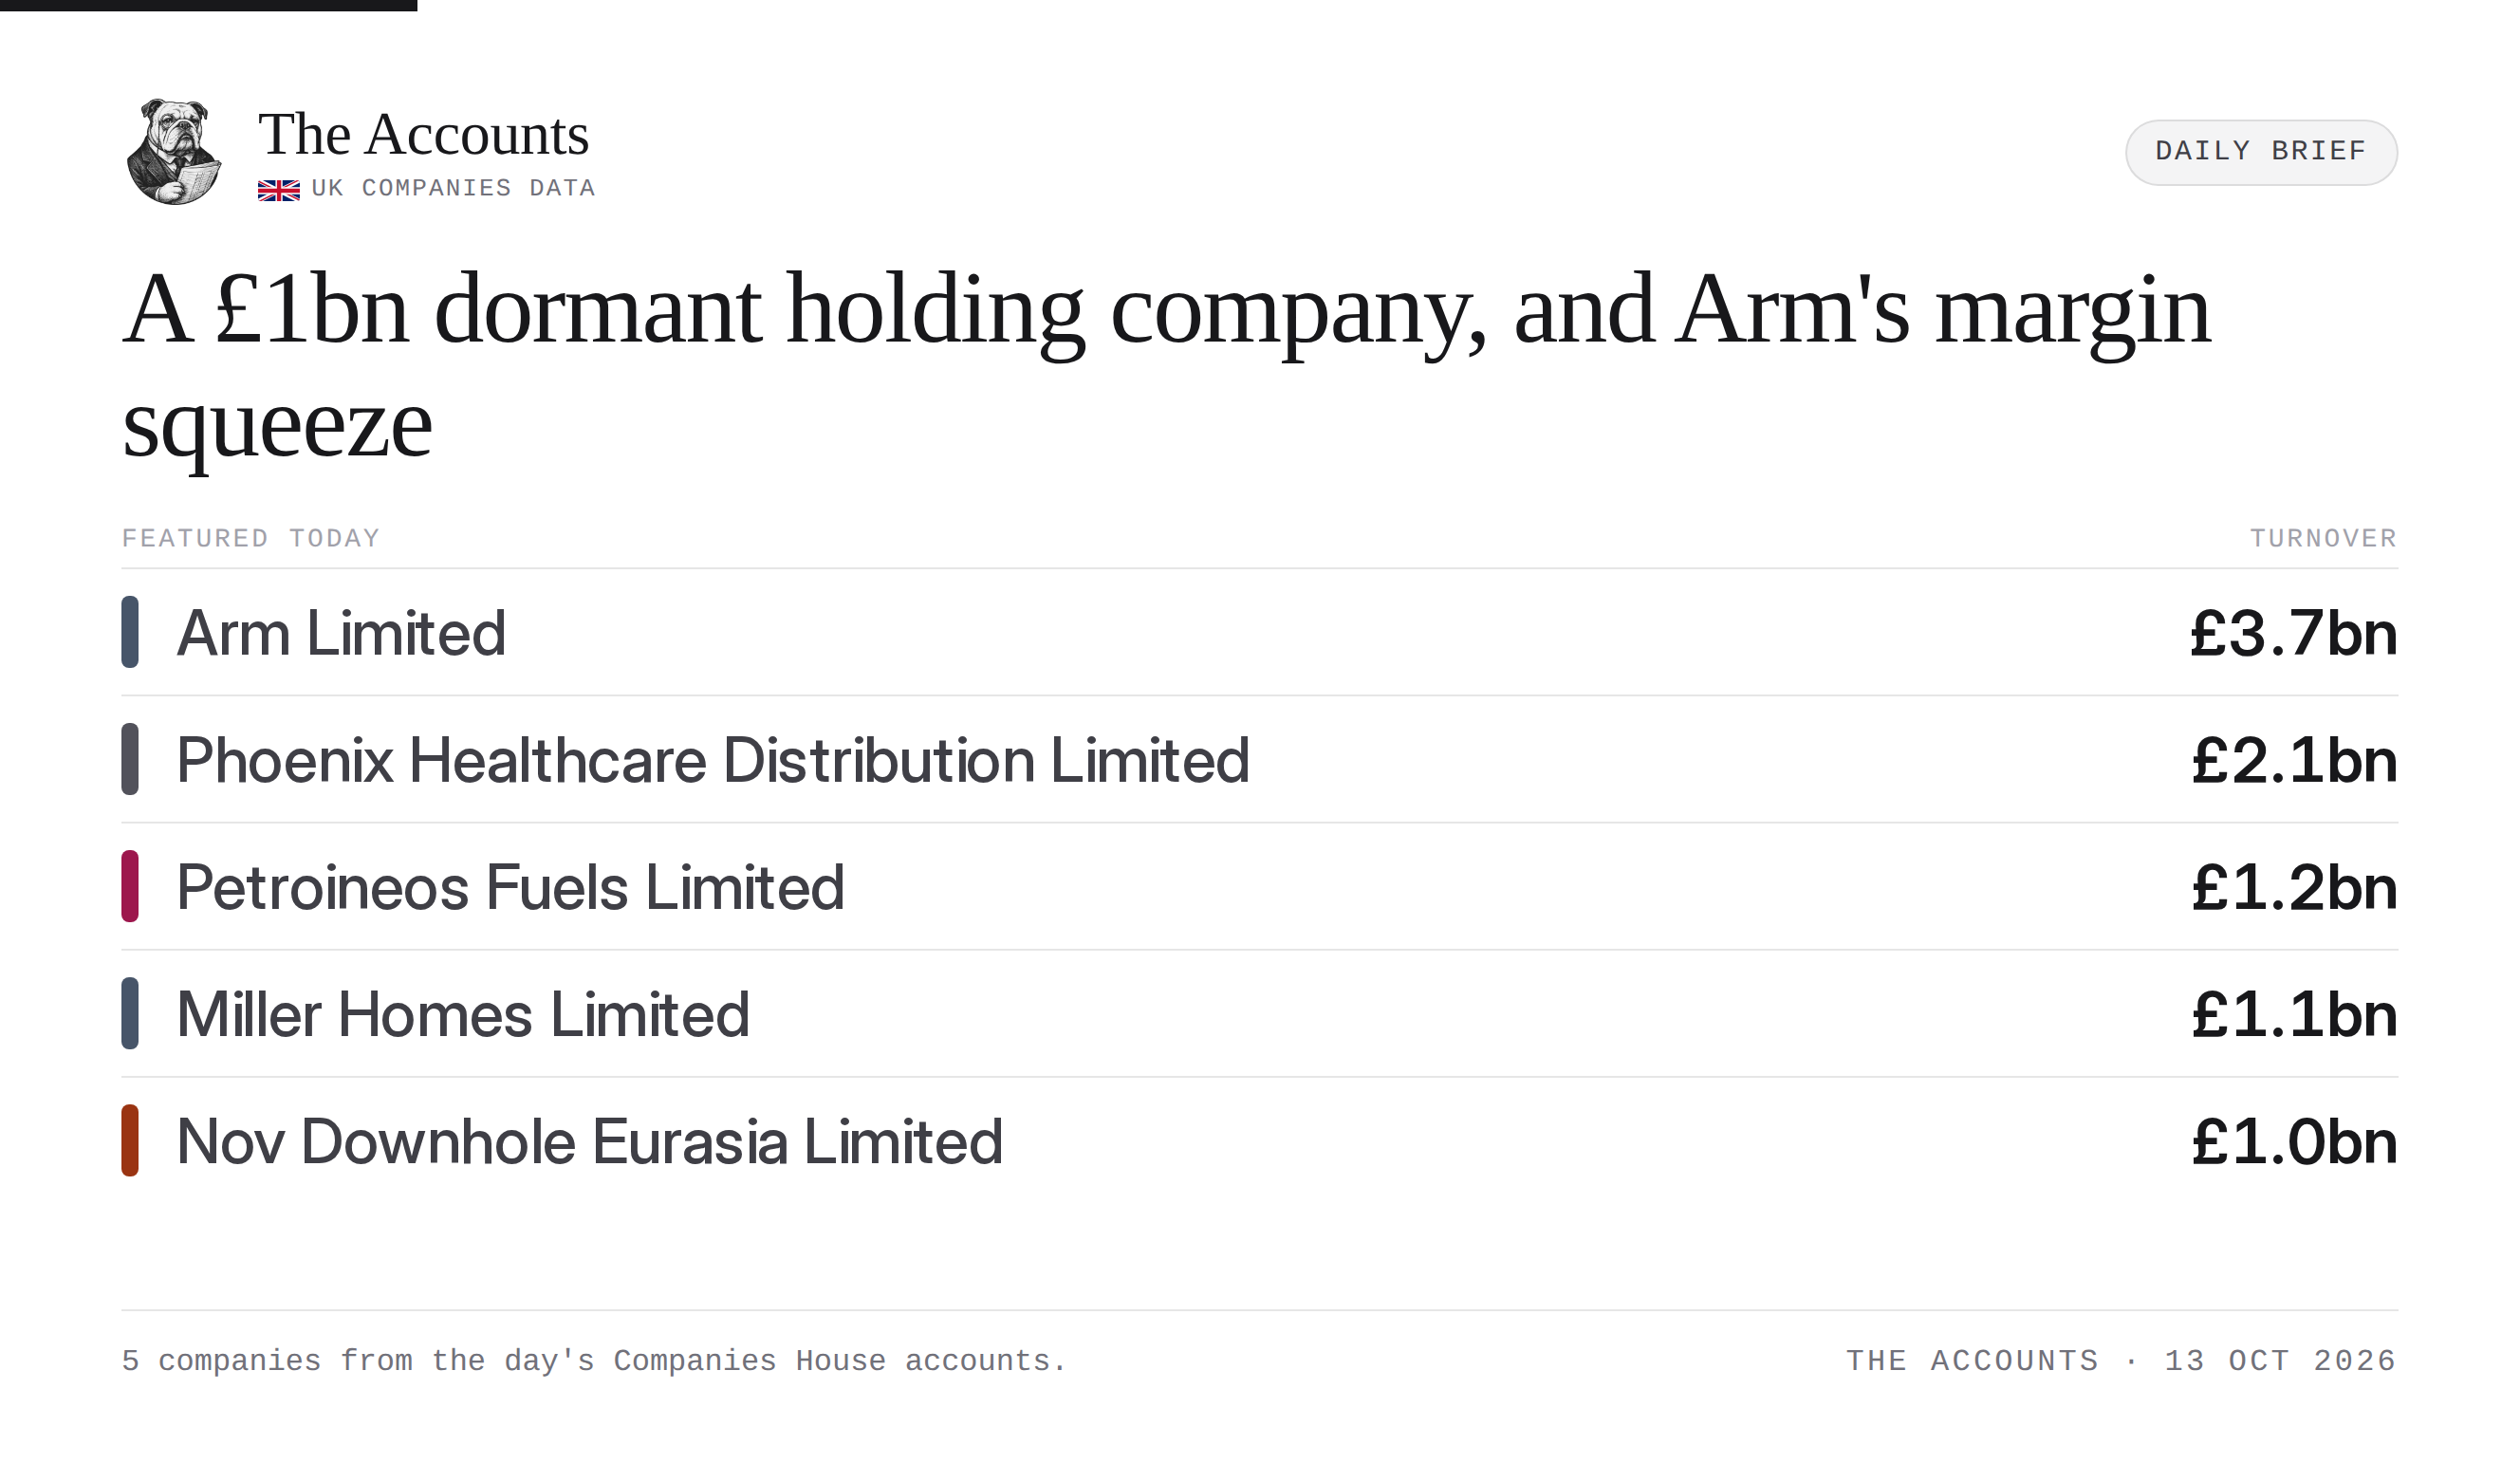
A £1bn dormant holding company, and Arm's margin squeeze
The takeaways
- Arm's turnover surged 23% to £3.7bn but operating profit fell 19% as administrative expenses expanded
- Petroineos revenue nearly halved to £1.15bn as the wider group shuttered refining at Grangemouth
- Headcount at NOV Downhole Eurasia dropped 11% but total staff costs still rose 5% to £174m
Hiring signals · who grew, who shrank
Hiring
- Zatu Limited 56 → 99 staff ▲ +77% staff cost +38%
- Macintyre Hudson Llp 1,029 → 1,665 staff ▲ +62% staff cost +60%
Cutting
- Goodrich Control Systems 630 → 352 staff ▼ −44% staff cost −42%
- Qul Technologies Limited 159 → 99 staff ▼ −38% staff cost −37%
Average headcount from the accounts filed yesterday — a look back at last year's payroll, not a live hiring tracker.
Filing of note
Linnaeus Group Limited
Operating via linnaeusgroup.co.uk, the company is a privately held UK provider of veterinary services, managing a network of specialist referral hospitals and first-opinion practices as a subsidiary of Mars Petcare.
Filed dormant while holding £1.05bn in net assets.
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Cash & balance sheet | |||
| Net assets | £1.1bn | £1.0bn | ▲ +3% |
| People & pay | |||
| Avg. headcount | 0 | 0 | |
Today's most unusual filing is a company filed as dormant while sitting on £1.05bn in net assets. This entity acts as a holding vehicle for Mars Petcare's veterinary acquisitions across the UK. The balance sheet expanded slightly from the prior year following a £33m conversion of loan balances into equity.
Arm Limited [1]
Operating as a key UK entity of the Nasdaq-listed Arm Holdings plc, which is majority-owned by SoftBank Group, the business designs and licenses semiconductor intellectual property including microprocessor and graphics processing unit architectures.
Squeezed margins
| Line | FY26 | FY25 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £3.7bn | £3.0bn | ▲ +23% |
| Gross profit | £3.6bn | £2.9bn | ▲ +23% |
| Admin expenses | £888.2m | £743.9m | ▲ +19% |
| Operating profit | £411.6m | £509m | ▼ −19% |
| Finance costs | £19.6m | £9.1m | ▲ +117% |
| Profit before tax | £540m | £595.9m | ▼ −9% |
| Net profit | £405.6m | £476.6m | ▼ −15% |
| Cash & balance sheet | |||
| Cash | £1.5bn | £1.0bn | ▲ +47% |
| Net assets | £2.5bn | £2.3bn | ▲ +9% |
| People & pay | |||
| Avg. headcount | 3,765 | 3,346 | ▲ +13% |
| Staff cost | £570.2m | £495.4m | ▲ +15% |
Revenue at the UK arm of the chip designer surged 23% to £3.7bn, but margins contracted alongside rising overheads. Operating profit dropped 19% to £411m as administrative expenses increased by £144m to £888m. The period also saw an expanding payroll, with average headcount rising by over 400 to 3,765.
Phoenix Healthcare Distribution Limited [2]
Operating as part of the PHOENIX Medical Supplies UK Group, the company is a wholesale distributor of pharmaceutical goods that sits alongside sister brands including Rowlands Pharmacy and Numark (phoenixmedical.co.uk).
Accounting boost
| Line | FY26 | FY25 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £2.1bn | £2.0bn | ▲ +9% |
| Gross profit | £188.5m | £145.8m | ▲ +29% |
| Admin expenses | £54.4m | £49.1m | ▲ +11% |
| Operating profit | £42.9m | £10.2m | ▲ +320% |
| Finance costs | £2m | £2.1m | ▼ −5% |
| Profit before tax | £41.2m | £68.1m | ▼ −40% |
| Net profit | £31m | £65.5m | ▼ −53% |
| Cash & balance sheet | |||
| Cash | £121k | £39.1m | ▼ −100% |
| Net assets | £138.9m | £108m | ▲ +29% |
| Dividends paid | £0 | −£230m | ▲ +100% |
| People & pay | |||
| Avg. headcount | 1,697 | 1,525 | ▲ +11% |
| Staff cost | £58.7m | £52.3m | ▲ +12% |
| Highest-paid director | £693k | £565k | ▲ +23% |
Operating profit appears to have quadrupled to £42.9m, but this reflects a structural accounting shift. The filing notes a move to principal accounting under IFRS 15 for its Nupharm Direct sales increased the reported top lines. Further down the P&L, profit before tax actually dropped 39% to £41.2m, as the prior year included a one-off £60m dividend from subsidiaries.
Petroineos Fuels Limited [3]
Formerly known as Ineos Fuels Limited, the company operates as a wholesale distributor of fuels and related products within the Petroineos joint venture, controlled by PetroChina.
Structural decline
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £1.2bn | £2.1bn | ▼ −43% |
| Gross profit | £57.3m | £94.7m | ▼ −39% |
| Operating profit | £57.3m | £94.7m | ▼ −39% |
| Finance costs | £2.3m | £2.9m | ▼ −21% |
| Profit before tax | £75.2m | £120.1m | ▼ −37% |
| Net profit | £70.1m | £113.7m | ▼ −38% |
| Cash & balance sheet | |||
| Net assets | £173.9m | £255m | ▼ −32% |
| Dividends paid | −£151m | — | |
| People & pay | |||
| Avg. headcount | 0 | 0 | |
The operational transition is clearly visible in the numbers. Turnover nearly halved to £1.15bn and operating profit dropped 39% to £57.3m as the wider group ceased refining operations at Grangemouth to transition to an import terminal. Despite the sharp contraction in sales, the entity still recorded a £151m dividend to its parent.
Miller Homes Limited [4]
Operating as a principal trading entity, the company is a British housebuilder focused on suburban family developments across Scotland, northern England, and the Midlands, ultimately owned by the US private equity firm Apollo Global Management.
Steady foundations
| Line | FY24 | FY23 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £1.1bn | £1.0bn | ▲ +5% |
| Gross profit | £220.8m | £207.9m | ▲ +6% |
| Admin expenses | £75.7m | £65.2m | ▲ +16% |
| Operating profit | £146.5m | £144.1m | ▲ +2% |
| Finance costs | £9.6m | £6.5m | ▲ +48% |
| Profit before tax | £149.7m | — | |
| Net profit | £128.8m | £139.5m | ▼ −8% |
| Cash & balance sheet | |||
| Cash | £234.3m | £194.2m | ▲ +21% |
| Net assets | £448.9m | £448.9m | ▲ −0% |
| People & pay | |||
| Avg. headcount | 1,118 | 1,148 | ▼ −3% |
| Staff cost | £90.9m | £84.5m | ▲ +8% |
| Director pay | £1.2m | £1.1m | ▲ +9% |
| Highest-paid director | £1m | £866k | ▲ +18% |
The sort of steady margins you can nap on. Turnover ticked up 4% to £1.05bn and operating profit held virtually flat at £146.5m for the Apollo-backed housebuilder. The directors note a slight improvement in the private sales rate to 0.65 homes per site per week, while noting an ongoing CMA probe into industry information sharing.
Nov Downhole Eurasia Limited [5]
NOV Downhole Eurasia Limited is a UK-based subsidiary of the American energy equipment multinational National Oilwell Varco, acting as a holding and operating entity that provides support activities for petroleum and natural gas extraction.
Payroll divergence
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £1.0bn | £1.0bn | ▼ −1% |
| Gross profit | £168.5m | £185.3m | ▼ −9% |
| Admin expenses | £142.6m | £137.2m | ▲ +4% |
| Operating profit | £55.7m | £73.5m | ▼ −24% |
| Finance costs | £14m | £17.3m | ▼ −19% |
| Profit before tax | £50.7m | £62.6m | ▼ −19% |
| Net profit | £35.8m | £43.4m | ▼ −17% |
| Cash & balance sheet | |||
| Cash | £90.8m | £62.1m | ▲ +46% |
| Net assets | £270.7m | £351.5m | ▼ −23% |
| Dividends paid | −£113.3m | £0 | |
| People & pay | |||
| Avg. headcount | 3,124 | 3,510 | ▼ −11% |
| Staff cost | £174.5m | £165m | ▲ +6% |
| Director pay | £427k | £428k | ▼ −0% |
| Highest-paid director | £362k | £378k | ▼ −4% |
This consolidated set shows turnover holding steady at £1.01bn, but operating profit slid 24% to £55.6m. It features a classic divergence on the payroll: average headcount fell by 11% to 3,124, yet total staff costs still climbed 5% to £174m.
I'll be by my bowl, contemplating the true meaning of principal versus agent.
Sources
- Arm Limited
- Phoenix Healthcare Distribution Limited
- Petroineos Fuels Limited
- Miller Homes Limited
- Nov Downhole Eurasia Limited