The Accounts · daily brief
26 October 2026
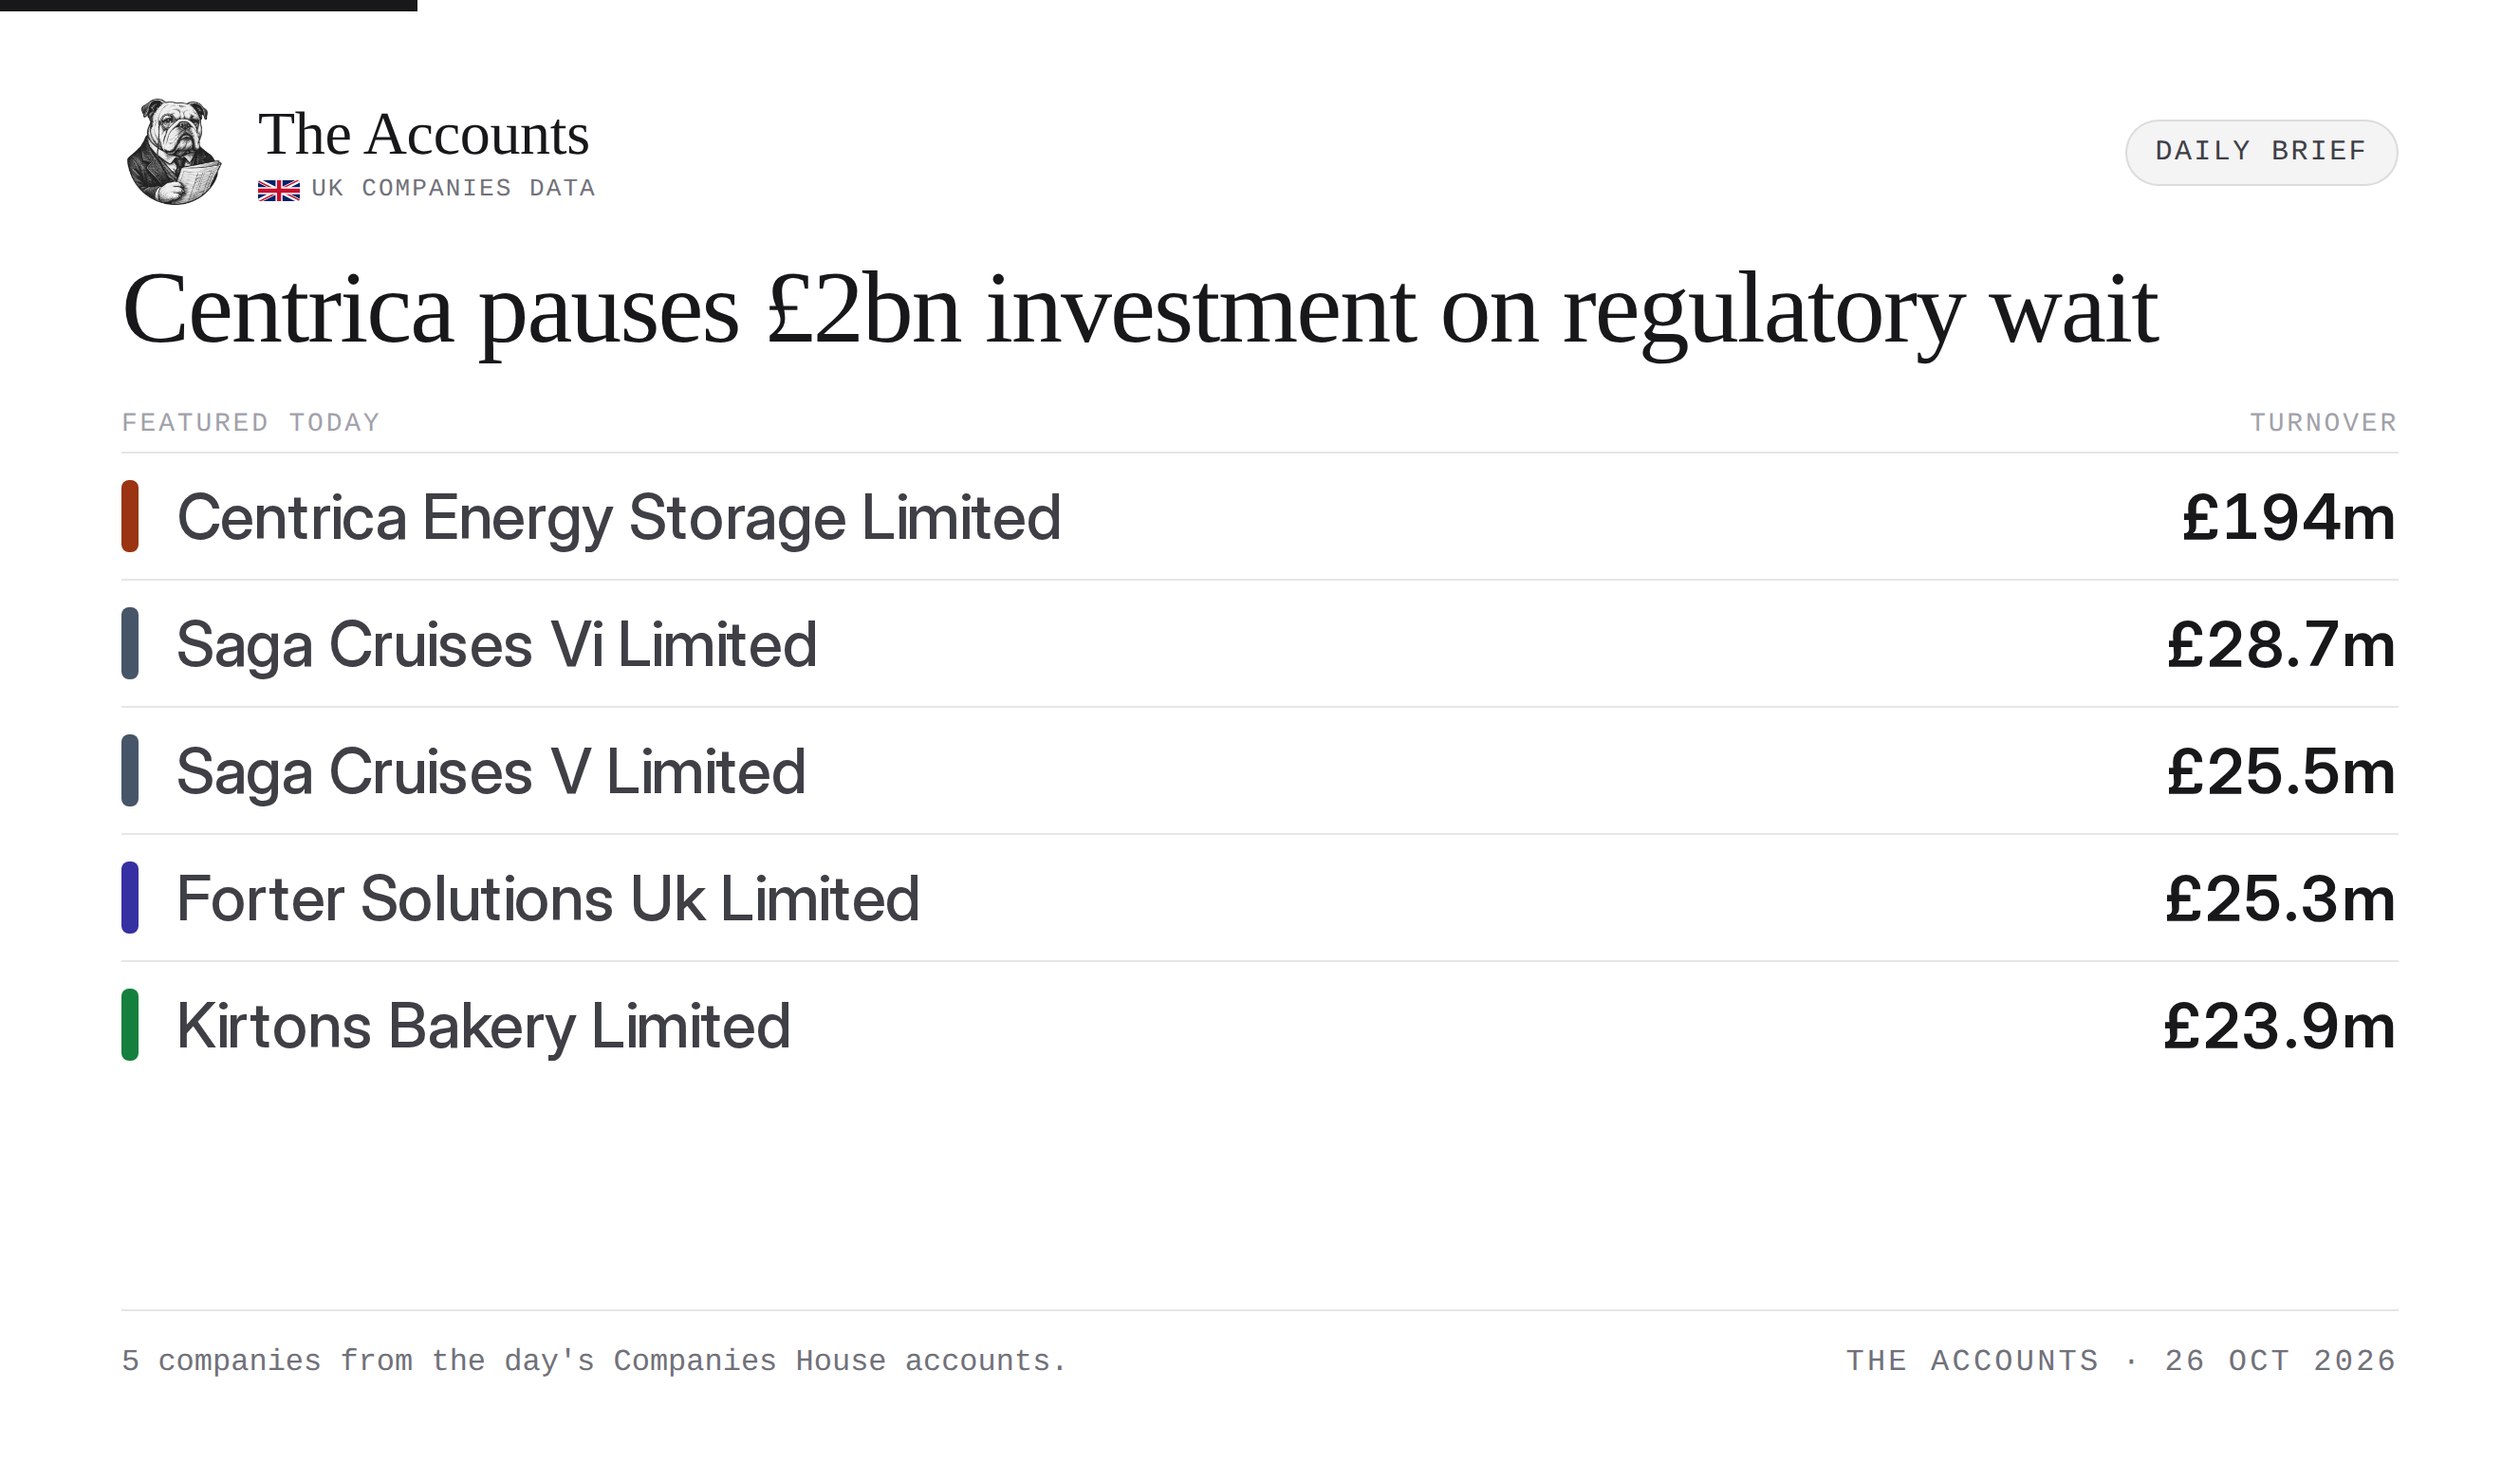
Centrica pauses £2bn investment on regulatory wait
The takeaways
- Centrica Energy Storage is withholding a £2bn investment in the Rough field pending a regulatory support model
- Saga's twin cruise ship entities remain reliant on parent funding to navigate heavy net current liabilities
- Kirtons Bakery pushed turnover up 23% to £23.9m, but rising input and utility costs squeezed operating profit
Hiring signals · who grew, who shrank
Hiring
- Forter Solutions Uk Limited 71 → 84 staff ▲ +18% staff cost +11%
- Kirtons Bakery Limited 147 → 162 staff ▲ +10% staff cost +25%
Cutting
- Hudsonbec Group Limited 53 → 46 staff ▼ −13%
Average headcount from the accounts filed yesterday — a look back at last year's payroll, not a live hiring tracker.
Centrica Energy Storage Limited [1]
Formerly known as Centrica Storage Limited, the business operates as a natural gas extraction, pipeline transport, and storage subsidiary of the listed British energy group Centrica plc.
Investment paused
| Line | FY24 | FY23 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £194m | £220m | ▼ −12% |
| Gross profit | £51m | £66m | ▼ −23% |
| Admin expenses | £18m | £6m | ▲ +200% |
| Operating profit | £33m | £32m | ▲ +3% |
| Finance costs | £1m | — | |
| Profit before tax | £45m | £152m | ▼ −70% |
| Net profit | £34m | £139m | ▼ −76% |
| Cash & balance sheet | |||
| Net assets | £46m | £13m | ▲ +254% |
| Dividends paid | — | −£250m | |
| People & pay | |||
| Avg. headcount | 239 | 223 | ▲ +7% |
| Staff cost | £27m | — | |
Accounts for the period ended 31 Dec 2024; prior column to 31 Dec 2023.
The numbers here are secondary to the strategic report. The filing notes the completion of all preparatory work for a £2bn investment to redevelop the Rough field for gas and hydrogen storage over the next 45 years. However, the capital remains uncommitted for now: the filing states that without a regulatory model to underpin it, the investment cannot proceed. For the record, operating profit held essentially flat at £33m on £194m in turnover.
Saga Cruises Vi Limited [2]
Saga Cruises VI Limited is a maritime subsidiary of the London-listed over-50s specialist Saga plc, serving as the specific corporate entity for the cruise ship Spirit of Adventure (saga.co.uk).
Asset holdco
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £28.7m | £29.1m | ▼ −1% |
| Gross profit | £16.8m | £18.7m | ▼ −10% |
| Finance costs | £8.2m | £9.3m | ▼ −12% |
| Profit before tax | £8.7m | £9.4m | ▼ −8% |
| Net profit | £8.7m | £9.4m | ▼ −8% |
| Cash & balance sheet | |||
| Net assets | £50.4m | £41.7m | ▲ +21% |
| People & pay | |||
| Avg. headcount | 0 | 0 | |
| Staff cost | £0 | £0 | |
| Director pay | £0 | £0 | |
Accounts for the period ended 31 Jan 2025; prior column to 31 Jan 2024.
This is the corporate wrapper for the Spirit of Adventure, operating entirely without direct employees. Turnover held broadly flat at £28.7m, which is entirely consumed by £8.2m in finance costs and £16.8m in cost of sales. The strategic report notes that ongoing geopolitical uncertainty and new tariffs require close monitoring, while the accounts rely on a letter of support from the parent group to support the going concern basis.
Saga Cruises V Limited [3]
This entity is a passenger cruise operating subsidiary of the London-listed over-50s specialist Saga plc, providing sea and coastal water transport as part of the group's wider holiday division (saga.co.uk).
Parent reliant
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £25.5m | £26.2m | ▼ −3% |
| Gross profit | £14.1m | £15.8m | ▼ −11% |
| Finance costs | £7.4m | £8.8m | ▼ −16% |
| Profit before tax | £6.7m | £7m | ▼ −4% |
| Net profit | £6.7m | £7m | ▼ −4% |
| Cash & balance sheet | |||
| Net assets | £47.5m | £40.8m | ▲ +16% |
Accounts for the period ended 31 Jan 2025; prior column to 31 Jan 2024.
The sister ship to the entity above, and a near-identical set of accounts. Turnover ticked in at £25.5m, but the balance sheet is carrying £88.9m in net current liabilities. The filing outlines that necessary funding has been secured from the intermediate parent to cover the gap. A newly agreed £485m group refinancing facility signed in January 2025 provides the required liquidity for the period ahead.
Forter Solutions Uk Limited [4]
Forter Solutions UK Limited is the British subsidiary of Forter, a US-headquartered software company providing fraud prevention and digital commerce trust solutions (forter.com).
Calendar quirk
| Line | FY26 | FY25 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £25.3m | £23.9m | ▲ +6% |
| Gross profit | £19.1m | £16.1m | ▲ +19% |
| Admin expenses | £15.7m | £18.7m | ▼ −16% |
| Operating profit | −£1.2m | −£2.7m | ▲ +55% |
| Profit before tax | −£1.1m | −£2.8m | ▲ +61% |
| Net profit | −£849k | −£2.8m | ▲ +70% |
| Cash & balance sheet | |||
| Cash | £2.7m | £3m | ▼ −8% |
| Net assets | £1.4m | −£32,641 | ▲ +4371% |
| People & pay | |||
| Avg. headcount | 84 | 71 | ▲ +18% |
| Staff cost | £18m | £16.3m | ▲ +11% |
| Director pay | £438k | £601k | ▼ −27% |
| Highest-paid director | £438k | £601k | ▼ −27% |
Accounts for the period ended 31 Jan 2026; prior column to 31 Jan 2025.
A quirk of the calendar here: the prior period ran for 13 months, making the unadjusted year-on-year comparisons slightly flattering. Even so, generating £25.3m in turnover in a standard year easily outpaces the £23.9m managed over the extended prior stretch. The filing attributes the growth to higher transaction volumes in the travel sector. It remains a loss-making enterprise, booking a £1.2m operating deficit, and relies on a letter of support from its Israeli parent.
Kirtons Bakery Limited [5]
Kirtons Bakery Limited is an independent, family-owned commercial bakery based in Leicester that manufactures bread, fresh pastries, and cakes.
Margin squeeze
| Line | FY26 | FY25 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £23.9m | £19.3m | ▲ +24% |
| Gross profit | £2.8m | £2.9m | ▼ −3% |
| Admin expenses | £1.2m | £1.2m | ▲ +0% |
| Operating profit | £1.7m | £1.8m | ▼ −5% |
| Profit before tax | £1.7m | £1.8m | ▼ −5% |
| Net profit | £1.5m | £1.5m | ▲ +2% |
| Cash & balance sheet | |||
| Cash | £4m | £4.6m | ▼ −13% |
| Net assets | £7.2m | £5.8m | ▲ +25% |
| Dividends paid | −£96,000 | −£96,000 | ▲ −0% |
| People & pay | |||
| Avg. headcount | 162 | 147 | ▲ +10% |
| Staff cost | £5.1m | £4.1m | ▲ +25% |
| Director pay | £97,173 | £145k | ▼ −33% |
Accounts for the period ended 18 Apr 2026; prior column to 18 Apr 2025.
A textbook case of top-line growth masking a margin squeeze. Turnover jumped 23% to £23.9m, but operating profit slipped slightly to £1.7m. The strategic report highlights the rising costs of raw materials and utilities, which are being addressed through supplier negotiations and pricing adjustments. Meanwhile, average headcount rose by 15 across the period, while total staff costs increased by 25% to £5.1m.
Proof that whether you're baking pastries in Leicester or storing hydrogen under the North Sea, the real money is always waiting on someone else's permission.
Sources
- Centrica Energy Storage Limited
- Saga Cruises Vi Limited
- Saga Cruises V Limited
- Forter Solutions Uk Limited
- Kirtons Bakery Limited