The Accounts · daily brief
30 October 2026
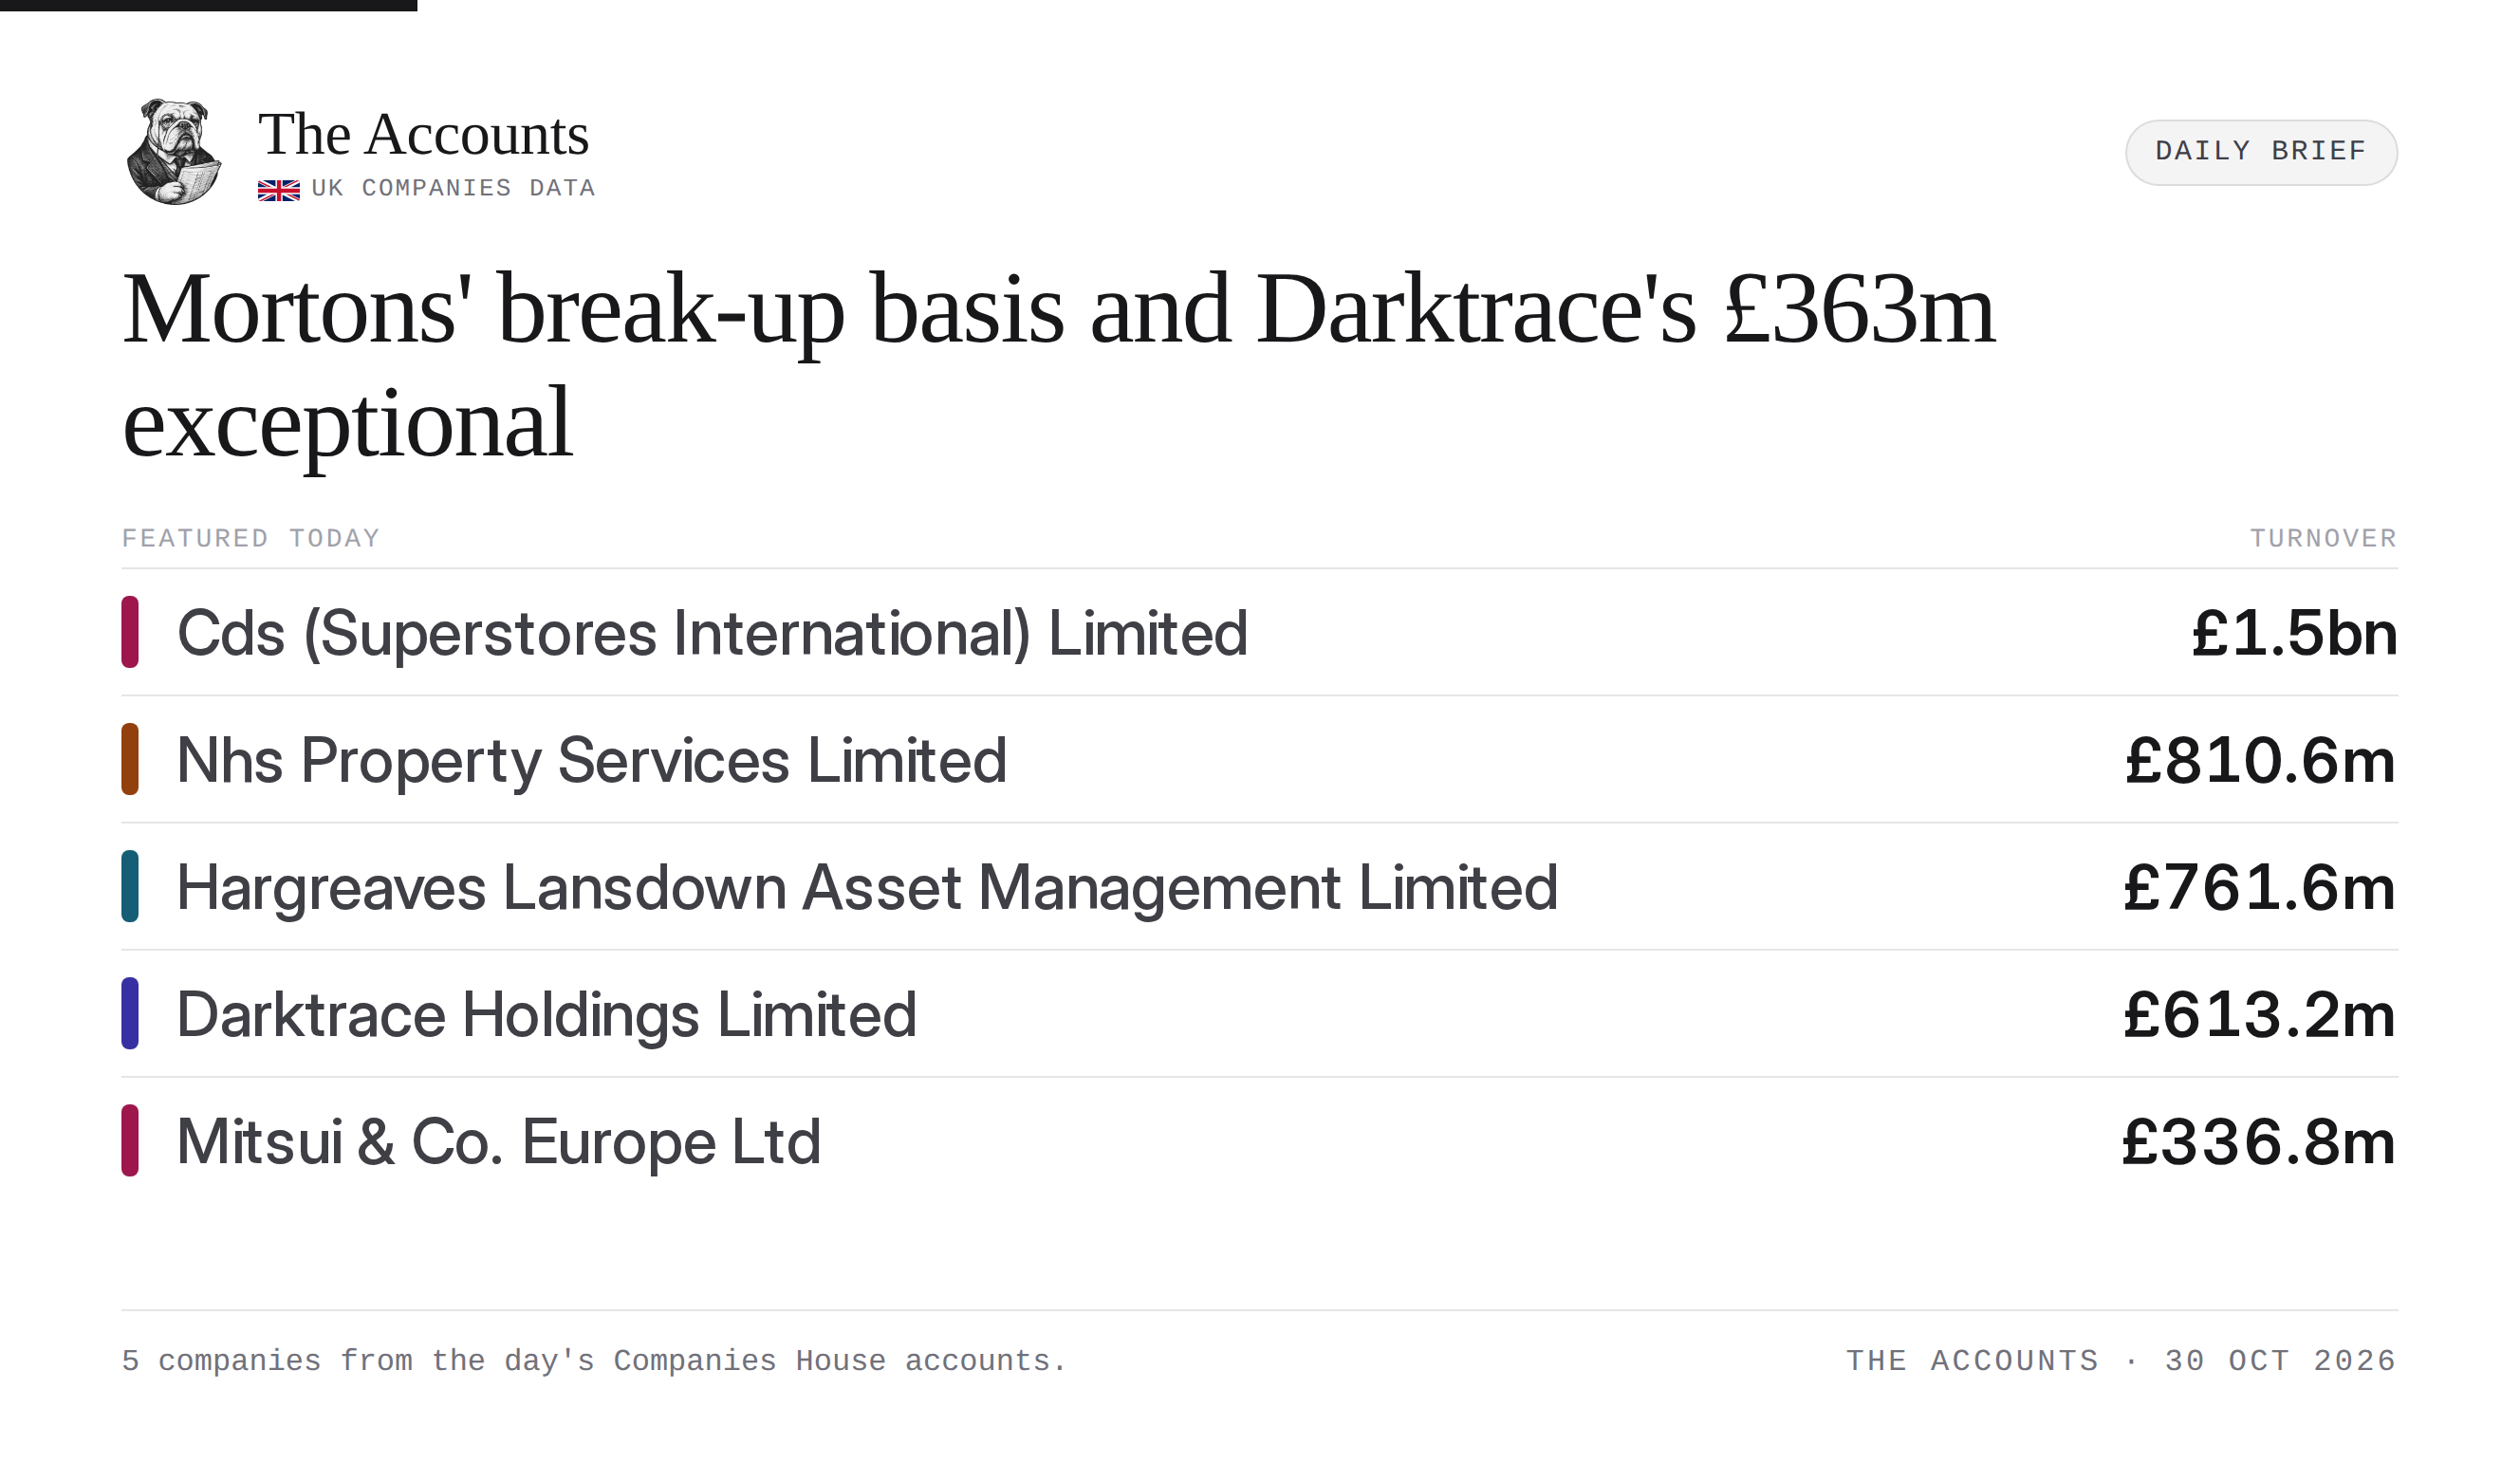
Mortons' break-up basis and Darktrace's £363m exceptional
The takeaways
- Mortons Media Group has filed on a break-up basis following the sale of its assets
- Darktrace recorded a £363m exceptional item, as profit before tax reached £427.6m
- The Range's operating profit stood at £50.2m alongside the integration of Wilko
Hiring signals · who grew, who shrank
Hiring
- Wood Leisure Holiday Parks Limited 86 → 112 staff ▲ +30% staff cost +22%
- Verkada Limited 141 → 183 staff ▲ +30% staff cost +38%
Cutting
- Mortons Media Group Ltd 128 → 22 staff ▼ −83% staff cost −82% accounts on a break-up basis
- The Creative Assembly Limited 683 → 383 staff ▼ −44% staff cost −47%
Average headcount from the accounts filed yesterday — a look back at last year's payroll, not a live hiring tracker.
Filing of note
Mortons Media Group Ltd
Mortons Media Group Ltd is a Lincolnshire-based publisher of specialist consumer periodicals, notably in the motorcycling sector, and operates enthusiast events under the Classic Bike Shows trading name as a subsidiary of Mortons Media Group Holdings Limited (mortons.co.uk).
Filed on a break-up (non-going-concern) basis — see the going-concern note.
| Line | FY26 | FY25 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £2.9m | £17.8m | ▼ −84% |
| Gross profit | £1.1m | £6.9m | ▼ −84% |
| Admin expenses | £707k | £3.2m | ▼ −78% |
| Operating profit | −£46,574 | £834k | ▼ −106% |
| Finance costs | £0 | £0 | |
| Profit before tax | £817k | £911k | ▼ −10% |
| Net profit | £773k | £683k | ▲ +13% |
| Cash & balance sheet | |||
| Cash | — | £3.7m | |
| Net assets | — | £2.6m | |
| Dividends paid | −£3.4m | −£1m | ▼ −231% |
| People & pay | |||
| Avg. headcount | 22 | 128 | ▼ −83% |
| Staff cost | £983k | £5.5m | ▼ −82% |
| Director pay | £175k | £411k | ▼ −58% |
| Highest-paid director | — | £128k | |
Accounts for the period ended 31 Jan 2026; prior column to 31 Jan 2025.
The accounts were prepared on a break-up basis following the sale of the print and mailing division. Turnover fell from £17.8m to £2.9m, while average headcount decreased from 128 to 22. The filing notes the transfer of the remaining trade to Kelsey Publishing, and records a £3.4m dividend paid in the year.
Cds (Superstores International) Limited [1]
CDS (Superstores International) Limited is the principal operating company for the privately owned UK home, garden, and leisure retail chain trading as The Range (therange.co.uk), which is controlled by The Range Home & Gardens Plc and also operates the Wilko brand.
Brand acquisitions
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £1.5bn | £1.3bn | ▲ +14% |
| Gross profit | £497.7m | £440.3m | ▲ +13% |
| Operating profit | £50.2m | £20.1m | ▲ +150% |
| Finance costs | £52.3m | £47.5m | ▲ +10% |
| Profit before tax | £541k | −£22.8m | ▲ +102% |
| Net profit | −£1.7m | −£16.9m | ▲ +90% |
| Cash & balance sheet | |||
| Cash | £41m | £76.3m | ▼ −46% |
| Net assets | £313.4m | £315.5m | ▼ −1% |
| Dividends paid | £0 | −£25m | ▲ +100% |
| People & pay | |||
| Avg. headcount | 12,639 | 12,238 | ▲ +3% |
| Staff cost | £217.8m | £188.6m | ▲ +15% |
| Director pay | £80,000 | £80,000 | ▲ −0% |
Accounts for the period ended 2 Feb 2025; prior column to 28 Jan 2024.
The accounts note the operating company's acquisition of Wilko's intellectual property and 53 Homebase stores. Turnover climbed 13.5% to £1.47bn. Alongside the improved trading performance, the filing records a £52.3m finance cost and a £1.7m net loss.
Nhs Property Services Limited [2]
Trading as NHS Property Services and operating via the domain property.nhs.uk, the company is a state-owned entity providing dedicated real estate and facilities management expertise to the National Health Service.
Going concern affirmed
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £810.6m | £807.9m | ▲ +0% |
| Gross profit | £65m | £59.7m | ▲ +9% |
| Admin expenses | £90.1m | £85.6m | ▲ +5% |
| Operating profit | −£87.7m | −£82.1m | ▼ −7% |
| Finance costs | £66.3m | £98.8m | ▼ −33% |
| Profit before tax | −£146.1m | −£174.6m | ▲ +16% |
| Net profit | −£138.3m | −£165.6m | ▲ +17% |
| Cash & balance sheet | |||
| Cash | £105.2m | £121.9m | ▼ −14% |
| Net assets | £3.0bn | £3.1bn | ▼ −1% |
| People & pay | |||
| Avg. headcount | 5,424 | 5,507 | ▼ −2% |
| Staff cost | £195m | £182.6m | ▲ +7% |
| Director pay | £792k | £708k | ▲ +12% |
| Highest-paid director | £293k | £293k | ▲ −0% |
Accounts for the period ended 31 Mar 2025; prior column to 31 Mar 2024.
The state-owned landlord's turnover was broadly flat at £810.6m, while operating losses widened to £87.7m. The filing attributes the deficit to non-cash depreciation charges and notes a £250m loan facility from the Department of Health and Social Care has been extended to 2027. The accounts were prepared on a going-concern basis, citing parent indemnities and a £3.04bn net asset position.
Hargreaves Lansdown Asset Management Limited [3]
Trading as Hargreaves Lansdown, the company is the principal FCA-regulated retail investment platform and pension provider subsidiary of the listed parent Hargreaves Lansdown plc, operating via hl.co.uk.
Takeover completed
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £761.6m | £679.7m | ▲ +12% |
| Admin expenses | £362.1m | £342m | ▲ +6% |
| Operating profit | £399.5m | £337.7m | ▲ +18% |
| Finance costs | £600k | — | |
| Profit before tax | £414.9m | £350.5m | ▲ +18% |
| Net profit | £303m | £258.9m | ▲ +17% |
| Cash & balance sheet | |||
| Cash | £316.9m | £252.7m | ▲ +25% |
| Net assets | £712.9m | £390.8m | ▲ +82% |
| Dividends paid | £0 | −£240m | ▲ +100% |
| People & pay | |||
| Avg. headcount | 2,229 | 2,272 | ▼ −2% |
| Staff cost | £198.7m | £179.7m | ▲ +11% |
| Director pay | £5.1m | £7m | ▼ −27% |
| Highest-paid director | £2.1m | £3.5m | ▼ −40% |
Accounts for the period ended 30 Jun 2025; prior column to 30 Jun 2024.
The accounts note the investment platform's principal subsidiary was acquired by Harp Bidco Limited in March 2025. Turnover rose 12% to £761.6m and operating profit reached £399.5m, while average headcount dipped slightly to 2,229. The firm posted a £303m net profit for the period.
Darktrace Holdings Limited [4]
Formerly known as Darktrace Limited, the entity serves as a principal software development and operating subsidiary for Darktrace Plc, a UK-based enterprise cybersecurity group specialising in AI-driven threat detection (darktrace.com).
Exceptional item
| Line | FY25 | FY24 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £613.2m | £517.7m | ▲ +18% |
| Gross profit | £520.3m | £470.6m | ▲ +11% |
| Admin expenses | £107.5m | £91.5m | ▲ +18% |
| Operating profit | £48.3m | £46.3m | ▲ +4% |
| Finance costs | £2.4m | £3.2m | ▼ −23% |
| Profit before tax | £427.6m | £52.6m | ▲ +712% |
| Net profit | £408.8m | £80.8m | ▲ +406% |
| Cash & balance sheet | |||
| Cash | £110.1m | £264m | ▼ −58% |
| Net assets | £598.4m | £211.2m | ▲ +183% |
| People & pay | |||
| Avg. headcount | 1,014 | 968 | ▲ +5% |
| Staff cost | £124.7m | £105.5m | ▲ +18% |
| Director pay | £2m | £1.5m | ▲ +31% |
| Highest-paid director | £1.3m | £1.1m | ▲ +16% |
Accounts for the period ended 30 Jun 2025; prior column to 30 Jun 2024.
Turnover at the cybersecurity group's main subsidiary rose 18% to £613.2m following its acquisition by Thoma Bravo. Operating profit held steady at £48.3m, while the accounts record a nine-figure exceptional item. Average headcount edged up to 1,014 as the filing notes continued acquisitions in cloud forensics.
Mitsui & Co. Europe Ltd [5]
Operating as the European headquarters for the Japanese multinational trading and investment conglomerate Mitsui & Co., the business engages in non-specialised wholesale trade and coordinates regional operations via its primary domain, mitsui.com/eu/.
Currency shift
| Line | FY26 | FY25 | YoY |
|---|---|---|---|
| Profit & loss | |||
| Turnover | £336.8m | £358.2m | ▼ −6% |
| Gross profit | £52.2m | £47.3m | ▲ +10% |
| Admin expenses | £76.4m | £67.2m | ▲ +14% |
| Operating profit | £1.2m | £3.5m | ▼ −66% |
| Finance costs | £16.4m | £12m | ▲ +37% |
| Profit before tax | −£1.5m | £496k | ▼ −399% |
| Net profit | £439k | £1.7m | ▼ −74% |
| Cash & balance sheet | |||
| Cash | £15.1m | £13.6m | ▲ +11% |
| Net assets | £255.7m | £106.4m | ▲ +140% |
| People & pay | |||
| Avg. headcount | 263 | 258 | ▲ +2% |
| Staff cost | £19.2m | £17.2m | ▲ +11% |
| Director pay | £3.3m | £2.8m | ▲ +18% |
| Highest-paid director | £1.7m | £1.6m | ▲ +7% |
Accounts for the period ended 31 Mar 2026; prior column to 31 Mar 2025.
The accounts note a shift in functional currency to US dollars to reflect underlying business activities. Expressed in sterling, turnover slipped 6% to £336.8m and operating profit fell to £1.2m. The company reported a £439k net profit, alongside £25.5m of other operating income, a £3.2m finance credit, and £76.4m in administrative expenses.
Whether integrating new brands or preparing accounts on a break-up basis, the filings capture the structural shifts.
Sources
- Cds (Superstores International) Limited
- Nhs Property Services Limited
- Hargreaves Lansdown Asset Management Limited
- Darktrace Holdings Limited
- Mitsui & Co. Europe Ltd